On the evening of August 27, *ST Konka (000016.SZ), once hailed as the “King of Color TVs,” announced that it plans to voluntarily withdraw its A-share and B-share listings from the Shenzhen Stock Exchange through a shareholder resolution. After the delisting takes effect, the company intends to transfer its shares to the National Equities Exchange and Quotations (NEEQ) for continued trading on the OTC board.
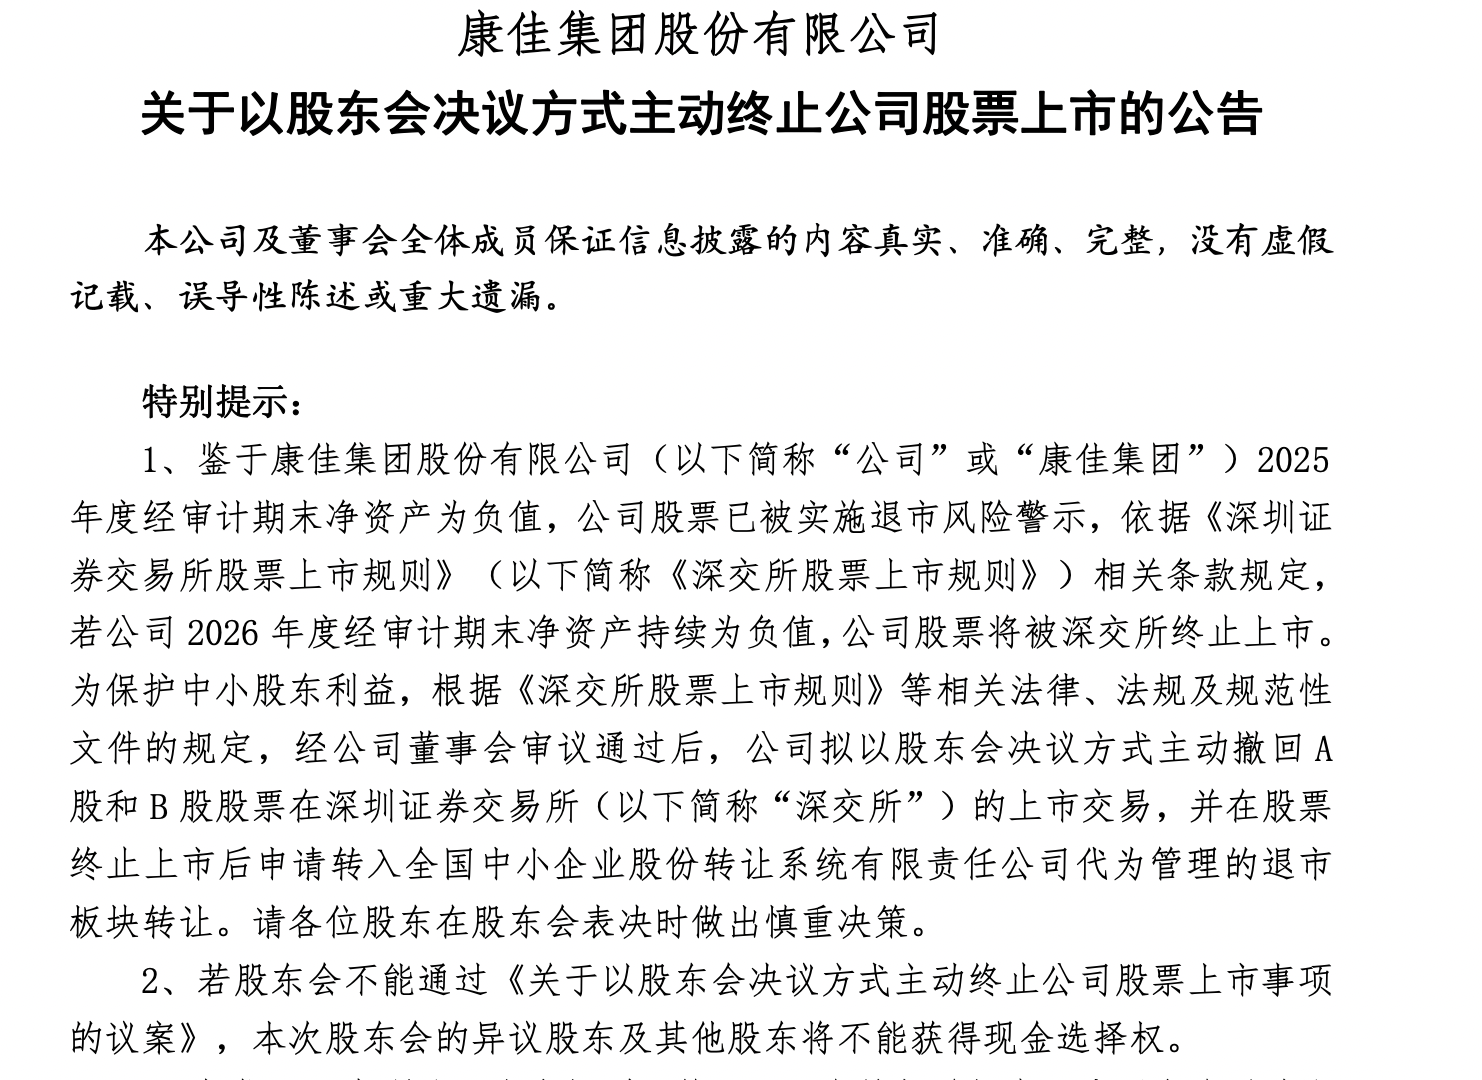
According to the announcement, *ST Konka’s audited net assets at the end of 2025 were negative, which triggered the delisting risk warning on its shares. If the net assets remain negative for the 2026 fiscal year, the stock would face mandatory termination of listing.
The company has set up a cash option for shareholders, with an exercise price of 2.48 yuan per A-share and 0.73 Hong Kong dollars per B-share, funded by Panshi Runchuang and Hemao Company respectively. This matter still needs to be approved by the shareholders’ meeting.
Konka stated that after the delisting, the company will maintain stable operations. At present, there are no plans for major asset restructuring, nor any specific timeline for relisting after the voluntary delisting.
On the same evening, Konka released its first-half 2026 earnings report, showing revenue of 3.852 billion yuan, down 26.60% year-on-year, and a net loss attributable to shareholders of 173 million yuan, compared with a loss of 383 million yuan in the same period last year.
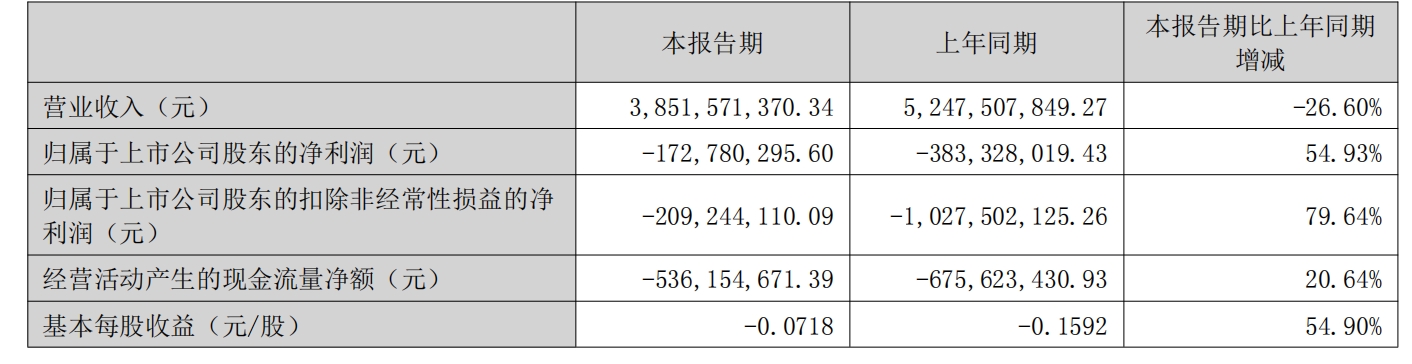
Explaining the losses, Konka said that in the first half of 2026, its consumer electronics business faced ongoing volatility in the upstream supply chain, driving up product costs. Adjustments to product mix and pricing strategies failed to offset the cost pressure, further squeezing gross margins. Although operating expenses continued to be optimized, the gross profit generated was not enough to cover these expenses, leaving the business in a loss-making position. Meanwhile, the semiconductor business remains in the early stages of industrialization. While some products have achieved commercial sales, the segment has yet to reach scale or profitability, and overall operations remain in the red.
According to the company’s official website, Konka Group was founded on May 21, 1980, and is recognized as the first Sino-foreign joint venture electronics enterprise established after China’s reform and opening-up. The company started with tape recorder production and built its first color TV assembly line in 1984.
In 1992, Konka’s A-shares and B-shares were listed on the Shenzhen Stock Exchange. The company has established more than ten production bases in cities including Chuzhou, Dongguan, Xinxiang, and Chongqing. It owns two major trademarks, KONKA/康佳 and Frestech, and operates 13 subsidiaries.
At its peak, Konka sold over 10 million TVs annually, ranked first in market share, and held the title of “King of Color TVs.” On July 22, 2025, following the completion and public announcement of the equity transfer for Konka’s specialized integration project, Konka came under the management system of China Resources (Holdings) Company Limited.
In recent years, Konka has suffered consecutive losses. Financial reports show that from 2022 to 2025, the company’s net losses attributable to shareholders were 1.723 billion yuan, 2.258 billion yuan, 3.726 billion yuan, and 12.582 billion yuan respectively, totaling over 20 billion yuan in four consecutive years of losses. As of the end of 2025, its debt-to-asset ratio had soared to 126.66%, with current liabilities reaching 18.314 billion yuan.
Amid the massive losses, multiple senior executives at Konka have been placed under investigation.
At the end of January this year, the “Huizhou Qingfeng” platform reported that Zhou Bin, former Party Secretary and Vice Chairman of the Board of Konka Group, and Li Hongtao, former Vice President of Konka Group, were suspected of serious disciplinary and legal violations. They were subject to disciplinary review by the Central Commission for Discipline Inspection’s disciplinary inspection team stationed at China Resources Group and supervisory investigation by the Huicheng District Supervisory Commission in Huizhou. Zhou Bin had long been in charge of the group’s operations and was a key figure in Konka’s previous wave of large-scale diversification.
In April, Liu Xitian, former Assistant President of Konka, was placed under investigation. In May, Yang Saiqing, Deputy General Manager of the group’s other business management department, and Li Yanbo, former Deputy General Manager of Konka Xinying Semiconductor, were reported in succession. In July, Guo Yimian, former Manager of a Konka venture capital subsidiary, was investigated.
In August, Yang Bo, former Vice President of Konka Group, was placed under investigation.Yang Bo assumed the role of Vice President of Konka Group in March 2017 and was involved in the expansion of the group’s smart terminal and industrial park businesses during his tenure, until he resigned from the vice presidency on January 12, 2026.
Annual report data shows that during Yang Bo’s tenure at Konka, his highest annual pre-tax compensation approached 3 million yuan, placing him among the group’s high-ranking management members. As of August last year, Yang Bo had no affiliations with shareholders holding more than 5% of the company’s shares, the actual controller, or other directors and senior managers, and he did not hold any company stock.