Staff Reporter |
News Editor | Wen Shuqi
In the first half of this year, RoboSense shipped nearly 2.7 times as many lidar units as it did during the same period last year. But the fastest-growing—and increasingly profitable—part of the business is no longer all about cars.
On August 26, RoboSense released its mid-year results for 2026. During the first six months, the company sold a total of 719,200 lidar units, a year-over-year jump of 169.6%. Of those, ADAS lidar units reached 436,600, up 98% year-over-year, while robotics and other applications accounted for 282,600 units, a staggering 510.4% increase. Over the same span, the company’s revenue hit RMB 1.02 billion, up 30.2%, with product revenue climbing 32.9% to RMB 958 million.
However, the surge in product sales didn’t translate into the anticipated profit boost. In the first half, RoboSense’s gross profit landed at RMB 222 million, up just 9.4%, and its overall gross margin slipped to 21.8% from 25.9% a year earlier. By the second quarter, revenue was up 23.2% year-over-year, but gross profit actually shrank by 2.8%. The net loss widened to RMB 96.62 million, a 93.9% expansion compared to the same period last year.
The company’s earnings report attributes the margin decline to lower average selling prices for lidar and rising raw material costs. Yet RoboSense is quick to point out that the drop in average pricing stems more from a shift in product mix than from cutthroat competition among rivals.
RoboSense’s Deputy CFO, Yun Juncun, explained during the earnings call that in the first quarter of last year, the company had virtually no sales of lidar for robotic lawnmowers. This year, those lower-priced products have driven a significant chunk of sales volume. The E1 blind-spot lidar, which also shipped in massive quantities during the same period, carries a lower price tag than the flagship automotive unit. Together, these two product lines at one point accounted for more than half of the company’s quarterly shipments.
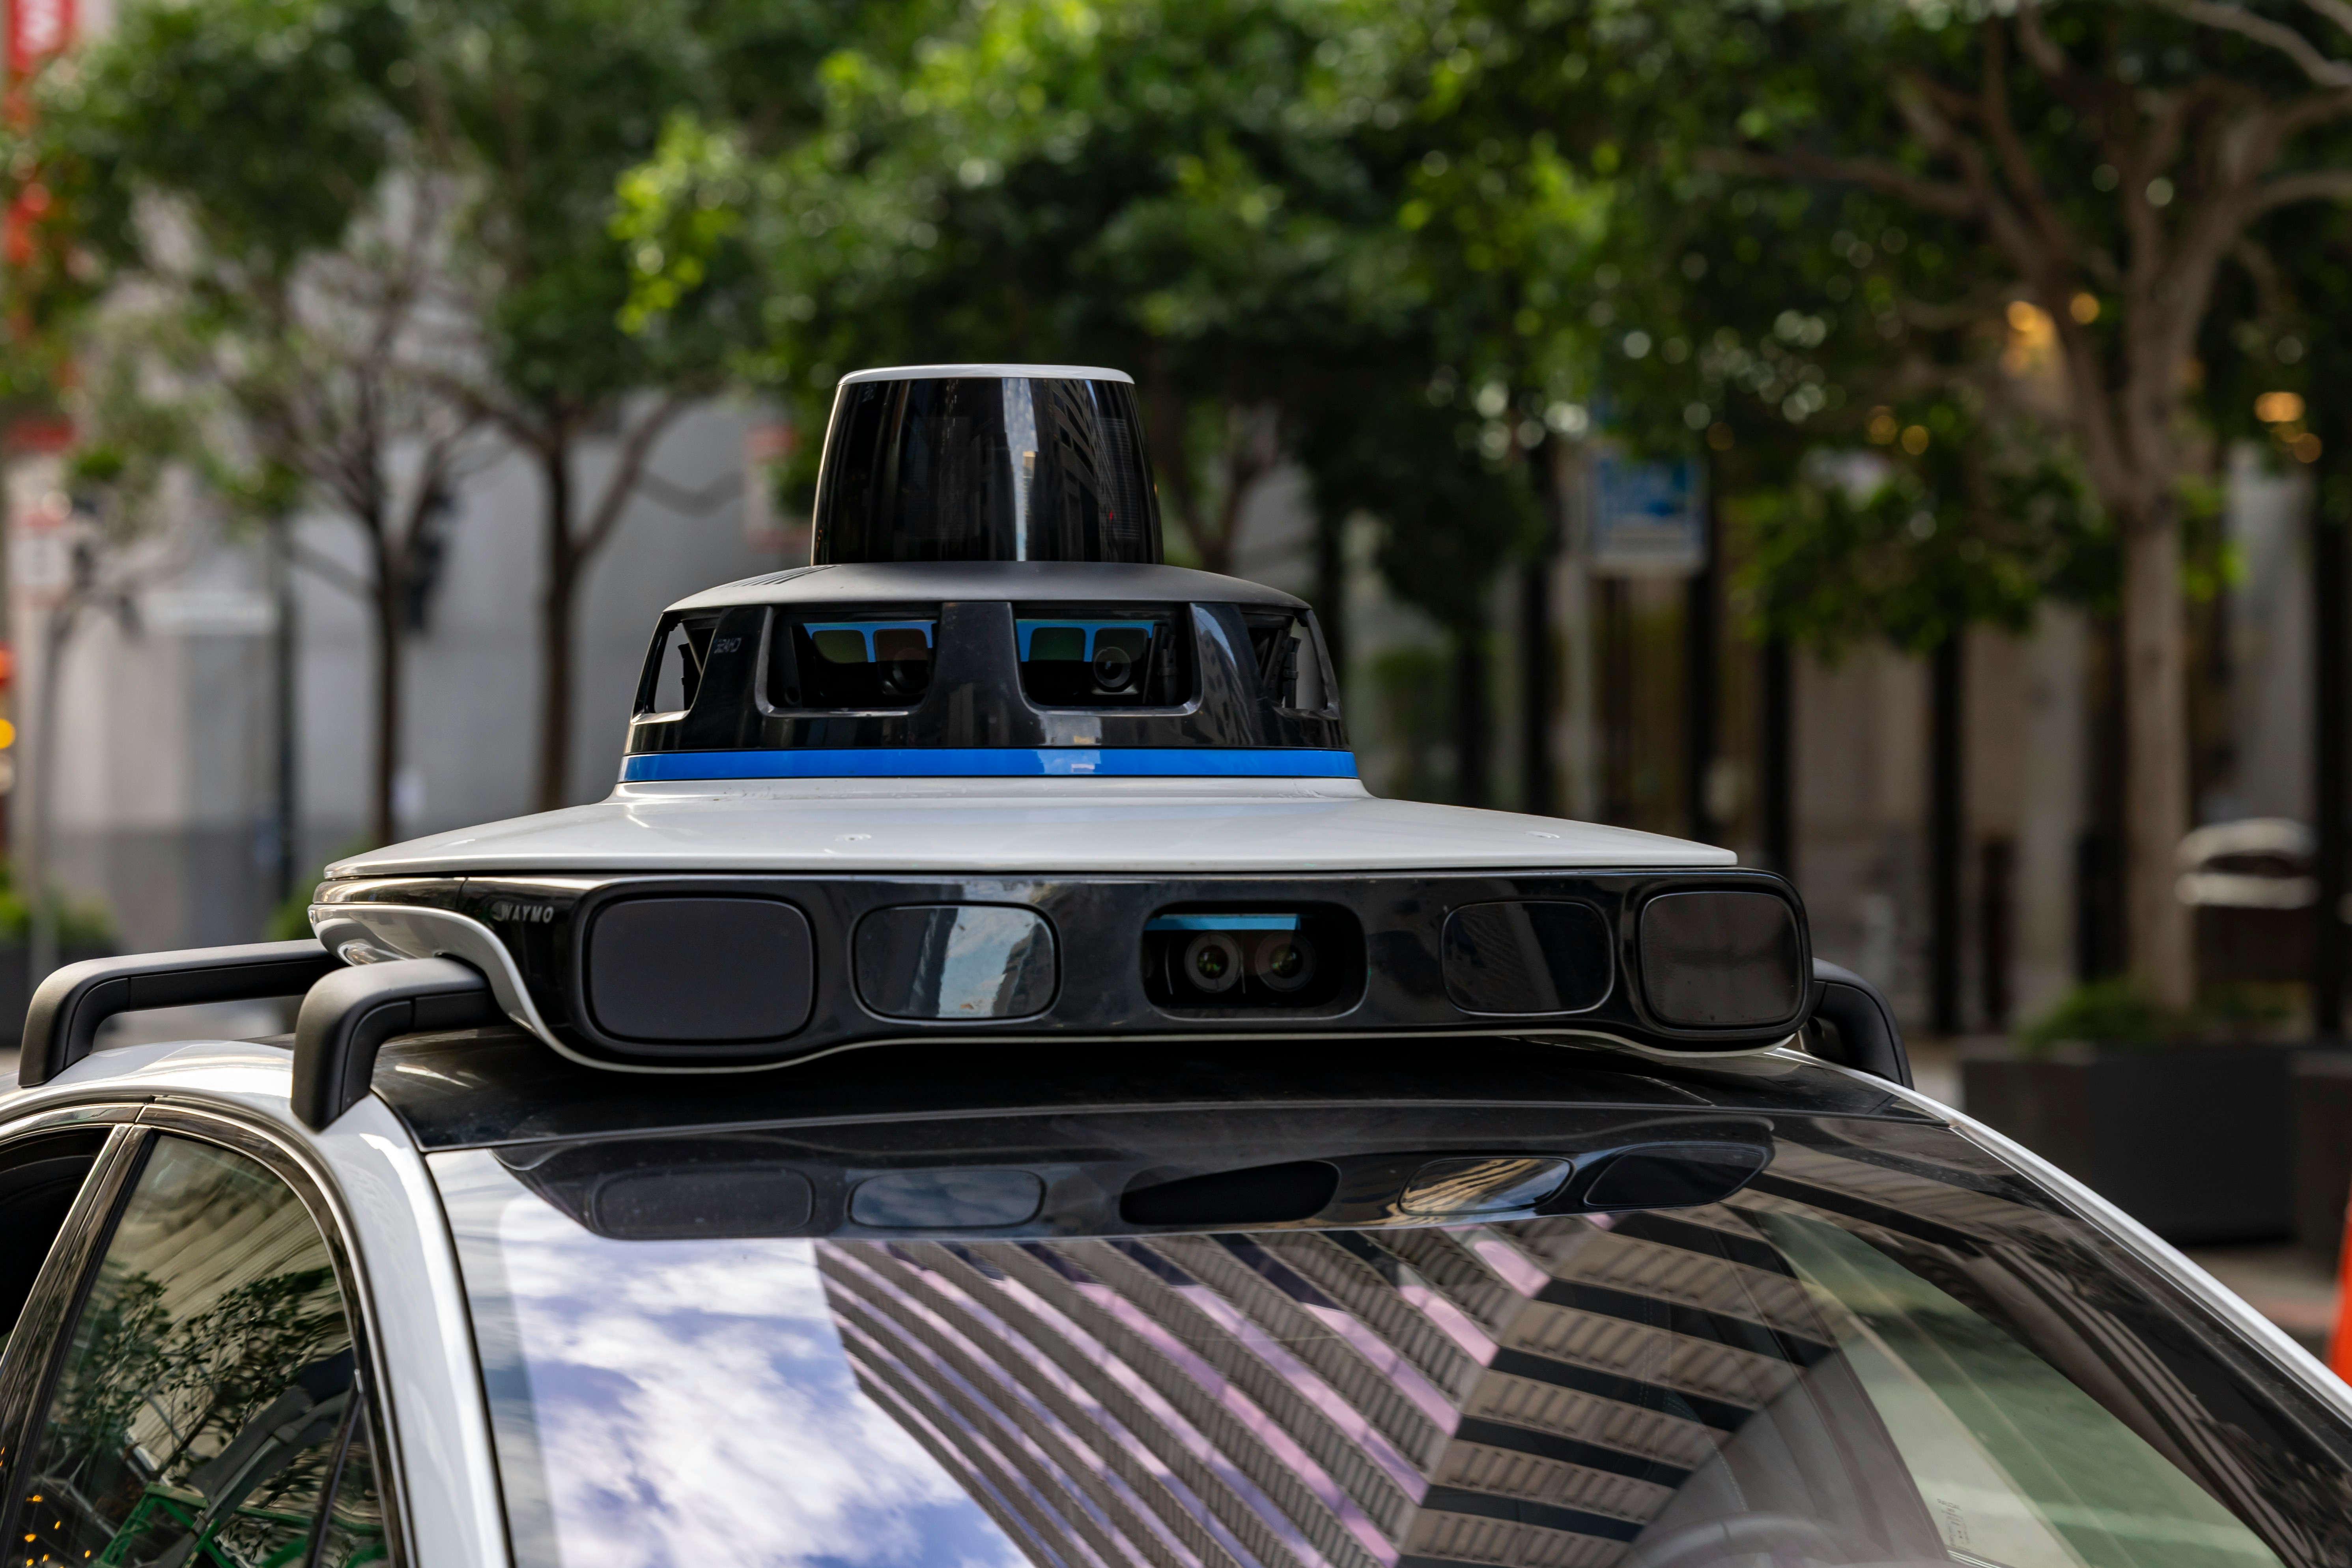
But there’s a hard-to-ignore backdrop here: lidar is entering a phase all too familiar in the auto parts world. The market keeps expanding, competition is getting fiercer, and individual units are getting cheaper by the day.
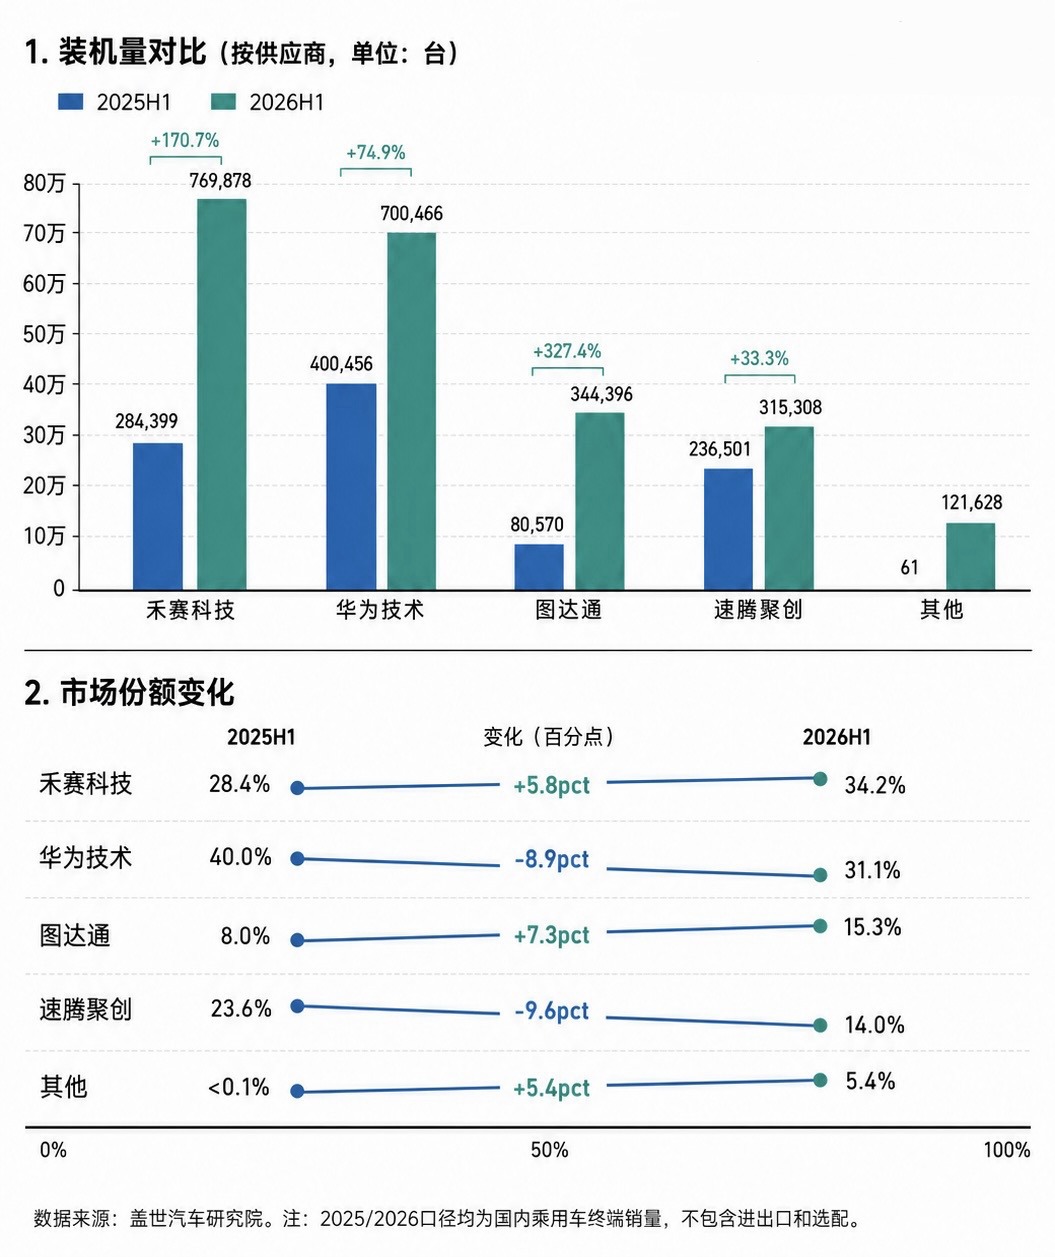
According to data from Gasgoo Auto Research Institute, domestic passenger car lidar installations hit roughly 1 million units in the first half of 2025. Just a year later, that figure had ballooned to around 2.25 million units. The market more than doubled, but the major suppliers didn’t split that growth evenly.
Hesai’s installations surged from 284,400 units to 769,900 units, a year-over-year gain of about 171%, pushing its market share from 28.4% to 34.2%. RoboSense’s installations also rose, from 236,500 units to 315,300 units, but that’s just a 33% increase, causing its market share to drop from 23.6% to 14%. Huawei’s share slid from 40% to 31.1%. By the first half of this year, Hesai and Huawei together had grabbed 65.3% of the market.
When factoring in optional configurations, RoboSense’s ADAS lidar sales reached 436,600 units in the first half of 2026, up 98.0% year-over-year. As of the end of June, the company had secured mass-production design wins for 186 vehicle models from 36 automakers and tier-1 suppliers, with 81 models already in SOP. By the time the mid-year report was released, that number had climbed further to 194 models.
Scaling up hasn’t stopped individual lidar units from getting cheaper. Hesai is one of the few manufacturers that consistently discloses average selling prices: its lidar ASP dropped from around $1,100 in 2023 to $530 in 2024, and further to $260 in 2025—a decline of more than three-quarters over two years. Hesai attributes this mainly to the rising share of lower-priced ADAS products in its mix.
As lidar continues to move downmarket from high-end autonomous driving models into the broader automotive market, relying solely on shipment volume is becoming a less effective way to stand out. The competitive battleground is shifting further upstream. RoboSense is pushing to migrate its ADAS products from traditional architectures to a digital architecture based on SPAD-SoC, and claims that roughly half of its ADAS shipments already use this approach. Once its self-developed chips enter mass production, the company expects related chip costs to drop by about 20%.
Meanwhile, lidar resolution just keeps climbing. Earlier this year, RoboSense unveiled what it calls the industry’s first automotive-grade single-chip SPAD-SoC, capable of outputting image-level resolution at 2,160 lines, with plans to push the next generation toward roughly 4,000 lines. Hesai has also laid out a product roadmap spanning 1,080, 2,160, and 4,320 lines, while giving its lidar the ability to perceive object colors. Lidar companies are under pressure to make their products cheaper on one hand, and to prove that pricier, higher-performance offerings still have a reason to exist on the other.
It’s also at this moment that robots have started to genuinely show up in RoboSense’s revenue mix.
In the first half of this year, the robotics business accounted for nearly half of RoboSense’s product revenue. The company says this segment contributed “almost all” of the product revenue growth during the period and has become the primary source of product gross profit.
This marks a turning point: beyond the automotive business, robotics has transitioned from a “second growth curve” that everyone was waiting for into a business big enough to reshape the company’s revenue and profit structure. It’s worth noting that this robotics category covers a wide range of scenarios, including robotic lawnmowers, commercial cleaning robots, autonomous delivery, and embodied intelligence. In the first quarter, lidar sales in this segment reached 185,500 units, before pulling back to 97,100 units in the second quarter—partly due to the pronounced seasonal stocking patterns of robotic lawnmowers.
On top of that, lidar companies are also starting to move deeper into the robot itself, following their customers.
In its mid-year report, RoboSense categorized its new robotics products as “eyes,” “skin,” and “muscles,” corresponding to spatial cameras, tactile sensors, and joint modules. The spatial camera, which simultaneously outputs color and depth information, has already secured volume orders and is slated to begin deliveries at the end of the third quarter. The first enterprise-level mass-production project for visuotactile and MEMS tactile products kicks off commercial deliveries at the end of September. As for joint modules, the company has generated an initial batch of demand in the tens of thousands and plans to start volume deliveries in the fourth quarter.
The customers for these sensors aren’t just robot manufacturers, either. Spatial cameras and tactile sensors are also making their way into robot data collection systems, where they’re used to generate hand-eye coordination training data.
RoboSense isn’t alone in this expansion. Hesai has already stretched its product lineup beyond traditional lidar into perception products that capture both spatial and color information, and has entered the robot joint and spatial data space. Ouster recently unveiled a new generation of native color lidar. Lidar makers used to sell a pair of “eyes” that measured distance. Now they’re fighting for a broader share of the sensors and components inside robots.
But what kind of eyes robots actually need is still far less clear than it is for cars.
One expert in embodied intelligence motion algorithms told NUPIAO that for a humanoid robot running at full speed, lidar is a relatively essential sensor. During high-speed movement, the robot needs to continuously determine its position relative to the surrounding environment, and that information feeds into real-time localization and navigation path planning.
But when you move a robot from the track to a specific real-world scenario, the answer changes. A technician working on embodied brain model development told NUPIAO that he doesn’t see lidar as a necessary sensor for desktop manipulation tasks. Even for depth maps provided by depth cameras, how neural networks can effectively use them is still not fully understood. “Some networks use depth maps, but performance doesn’t improve much—let alone with lidar.”
In his observation, when lidar is mounted on a wheeled chassis, its clearest use case remains navigation. But when a robot is standing at a table, needing to grab a cup, tidy up objects, or operate tools, whether the point clouds generated by lidar can serve as effective input for embodied large models—the way images do—remains an open question with no clear answer yet.
Automotive once transformed lidar from an expensive sensor found on autonomous driving test vehicles into a standardized component shipped in the millions each year. Robots are now offering a second market, but that market hasn’t yet settled on a unified technical path.
For RoboSense, that uncertainty doesn’t stop robotics from becoming a real business first. In the first half of this year, it already approached half of product revenue and became the main source of product gross profit. But what RoboSense is betting on in robotics is no longer just a single lidar unit—it’s spatial cameras, tactile sensing, joints, and a still-evolving system for robot perception and execution.