Staff Reporter | Song Jianan
“AI has hit an inflection point, and every token is generating productivity and profit.” Nvidia CEO Jensen Huang’s words were emphatically validated by capital markets with a trillion-dollar market cap surge right after the earnings report landed.
At Thursday’s close on August 27, Nvidia shares jumped 8.74% to $227.98, pushing its total market cap to a staggering $5.49 trillion. The company added a whopping $441.5 billion in a single session—roughly 2.97 trillion yuan—marking the second-largest single-day market cap gain in U.S. history, trailing only Microsoft’s record $450 billion surge.
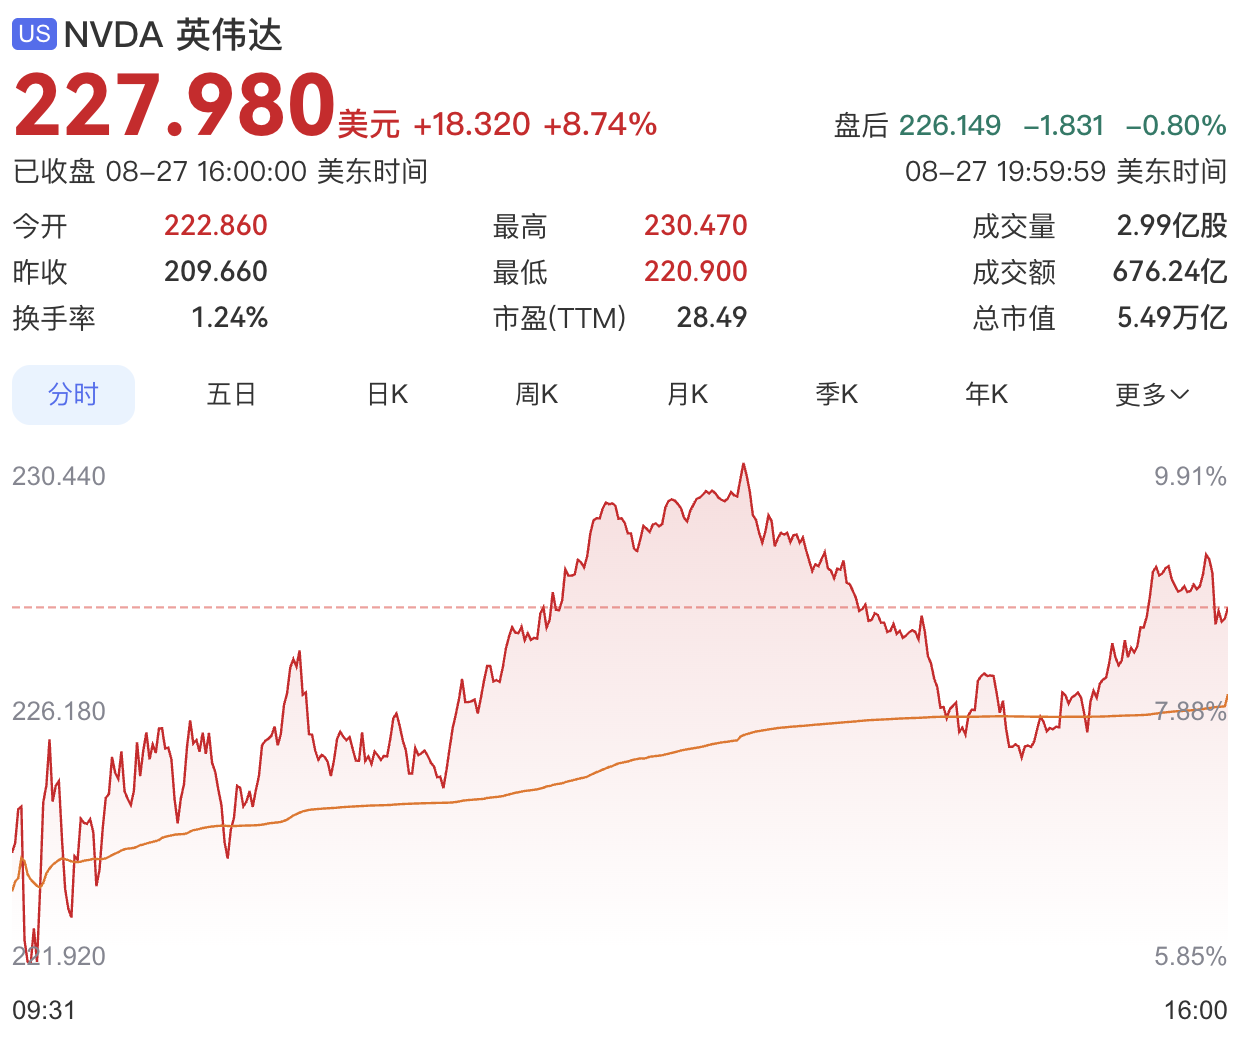
Just a few trading days earlier, this AI chip behemoth had been nursing a brutal pullback, sliding for seven straight sessions—its longest losing streak since September 2022. On August 24 alone, it shed $151 billion in market value (around 1.02 trillion yuan), dragging its total cap back to the $5.05 trillion neighborhood.
Back then, anxiety was running high across the market. Rising U.S. Treasury yields were weighing on richly valued tech names, and a growing chorus of investors started debating whether the AI capital expenditure cycle was nearing its peak. Many chose to flee to safety ahead of the earnings release.
Three sessions later, Nvidia staged a dramatic comeback, driven by its newly released Q2 FY2027 financial results.
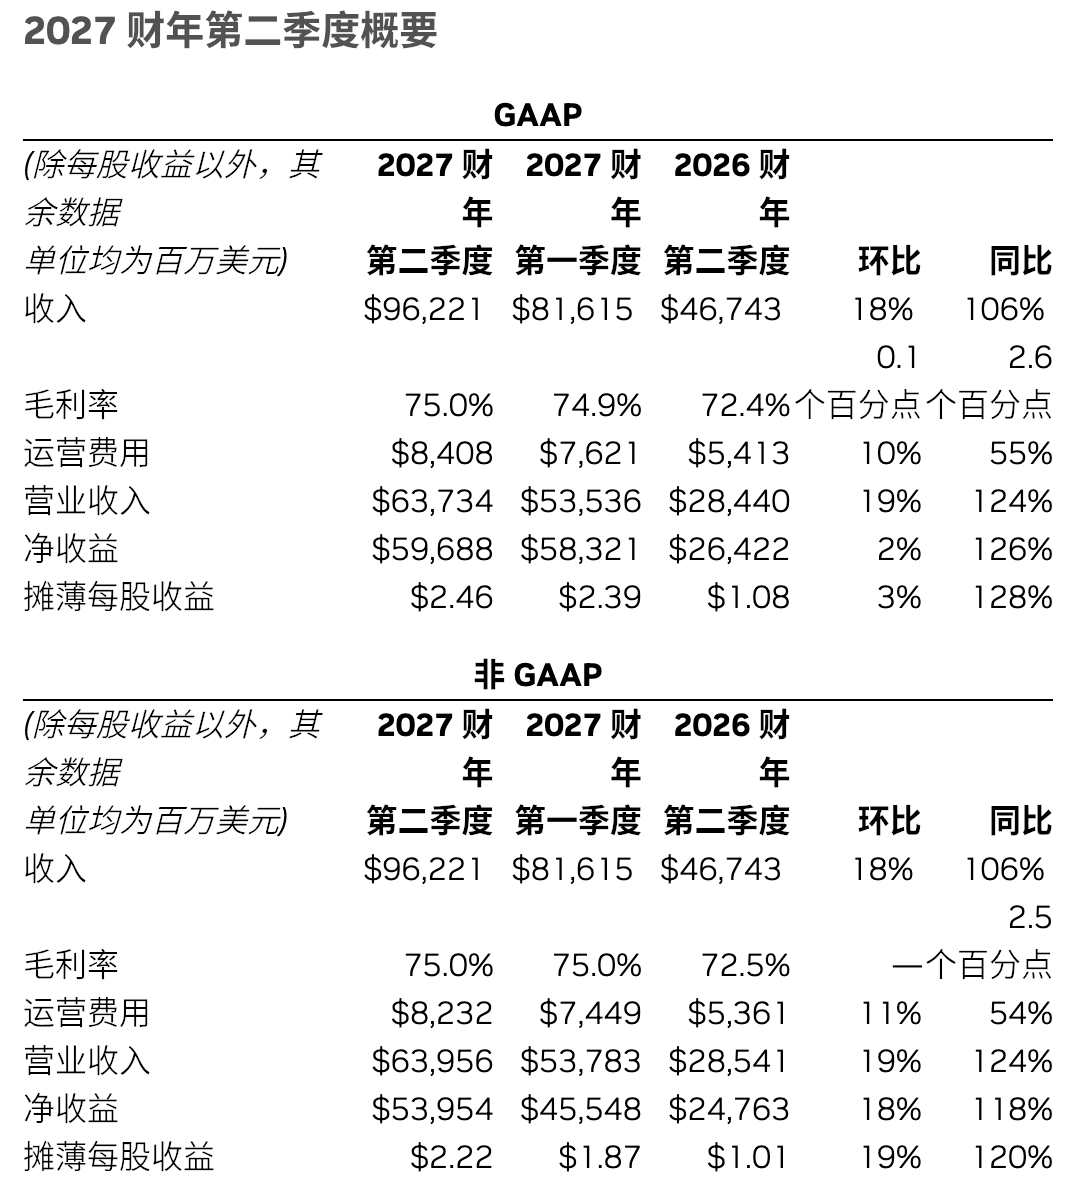
The report, covering the period through July 26, showed quarterly revenue hitting $96.221 billion—up 106% year-over-year and 18% quarter-over-quarter. Both GAAP and non-GAAP gross margins held strong at 75.0%, while non-GAAP diluted EPS came in at $2.22, blowing past Wall Street’s consensus expectations.
The data center business remains the undisputed growth engine, generating $89 billion in quarterly revenue—a 117% year-over-year surge—and accounting for the lion’s share of the company’s revenue expansion. Nvidia’s next-gen Vera Rubin platform has now entered full-scale production, with multiple software and hardware products for AI agents and physical AI rolling out simultaneously. The company also announced partnerships with major global financial institutions to channel over $500 billion in third-party capital into AI infrastructure, further widening the industry’s growth runway.
But what really juiced the stock was management’s forward guidance. Nvidia projected Q3 FY2027 revenue of approximately $108 billion, plus or minus 2%. Notably, this outlook excludes data center compute revenue from mainland China and Hong Kong. GAAP and non-GAAP gross margins are expected to land at 74.0%, plus or minus 50 basis points.
In the subsequent earnings call, Nvidia did something unprecedented—it offered a rare full-year growth preview. The company guided for roughly 70% year-over-year revenue growth in FY2028, a figure that towers above the market’s prior 45% consensus and marks the first time Nvidia has ever issued a full-year revenue growth outlook.
Huang told analysts on the call that actual market demand is growing faster than that 70% guidance, and that supply constraints—not demand—are the real bottleneck limiting further expansion.
In the immediate aftermath of the release, the market reaction was oddly mixed. Nvidia shares briefly dipped in after-hours trading as some traders fixated solely on the quarterly numbers.
But once management unpacked key details—long-term order backlogs, supply constraints, and the full-year guidance—sentiment shifted sharply. Investors quickly repriced Nvidia’s long-term value proposition. The market’s focus pivoted from “how much did they make this quarter?” to “how much further can the AI compute growth cycle run?” Massive undelivered orders from cloud providers, fresh compute demand from AI agents and physical AI, and a global wave of AI factory construction all combine to form a solid foundation for sustained high growth.
Following the earnings release, Wall Street wasted no time in launching a wave of price-target hikes. Over a dozen major investment banks updated their research notes in unison, turning broadly bullish on Nvidia’s trajectory. At least 13 institutions raised their price targets, according to preliminary tallies.
Among them, Raymond James led the charge, lifting its target from $352 to $515—now the highest on the Street—implying a market cap near $12.4 trillion. Goldman Sachs raised its target from $285 to $300 while reiterating a Buy rating. Goldman analyst James Schneider argued that if Nvidia continues collaborating with tech firms on data center buildouts and narrows the gap between customer demand and supply, the company could outperform even its FY2028 guidance.
Charu Chanana, chief investment strategist at Saxo Markets, noted that Nvidia’s biggest positive isn’t the quarterly beat itself, but management’s ~70% FY2028 revenue growth guidance—a powerful rebuttal to the “AI capex cycle has peaked” narrative.
Of course, beneath the institutional optimism, the market hasn’t turned a blind eye to potential risks. Several brokerage reports flagged that rising costs for HBM and other memory chips could pressure gross margins in coming quarters. Geopolitical policy shifts, competitive in-house chip development from rivals, and global macroeconomic volatility could all disrupt future earnings delivery. Nvidia itself acknowledged in its forward-looking statements that actual results may differ materially from current expectations.
From a seven-day losing streak to a historic single-day surge, Nvidia’s violent stock swings transcend any single company’s earnings narrative. At its core, this is a collective vote by global capital markets on the trajectory of the AI industry cycle. But whether the company can keep delivering on its lofty growth guidance is a question that only future quarterly results will answer.