Reporter | Song Jianan
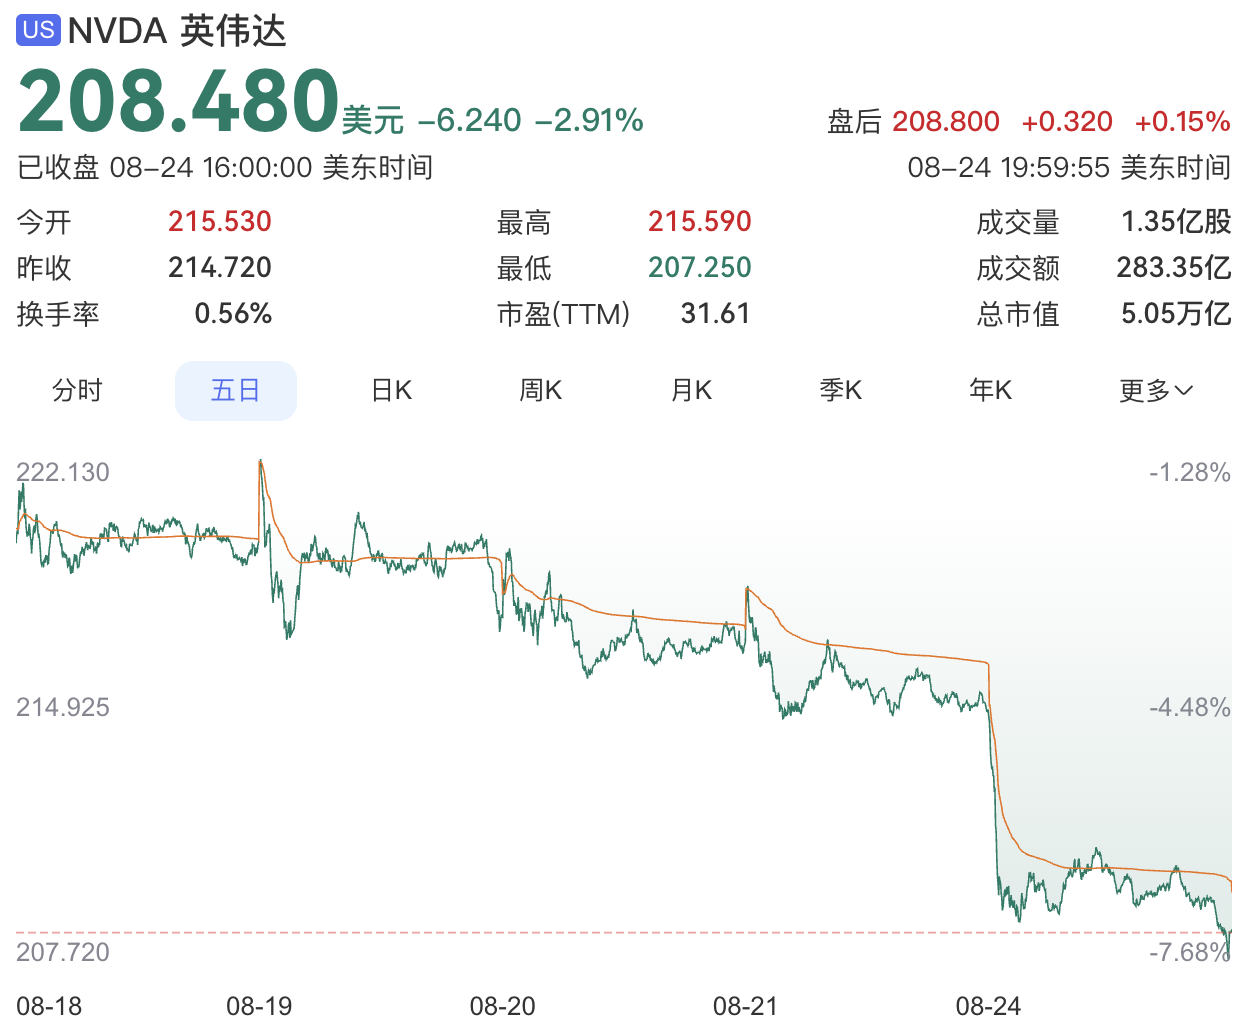
On August 24, Eastern Time, Nvidia closed at $208.48 per share, down 2.91%. The stock has now fallen for seven consecutive trading sessions, with cumulative losses of 7.5% during that stretch — the longest losing streak in four years, dating back to September 2022. Compared to its all-time closing high of $235.74 on May 14, the shares are now down more than 10%.
The company’s market cap shrank by $151 billion in a single day — roughly 1.02 trillion RMB — pulling its total valuation back to the $5.05 trillion range. Still, it holds onto its position as the most valuable company on the U.S. stock market.
Looking at the broader tape, a clear divergence emerged among U.S. tech heavyweights. On the same trading day, Meta and Amazon each gained 1.66% and 1.33%, respectively, while Microsoft, Google, and Apple also held onto modest gains. In sharp contrast, the hardware supply chain took a beating across the board. The Philadelphia Semiconductor Index dropped 2.7%, Micron Technology plunged 5.83%, Seagate and SanDisk both fell more than 6%, and AMD, Intel, and TSMC all closed lower. The optical communications sector also got hammered. Tesla tumbled 3.83%, making it the other big decliner among the “Magnificent Seven” besides Nvidia.
Meanwhile, the Nasdaq composite slipped 0.76% for the day. The Dow Jones Industrial Average managed a modest 0.26% gain, propped up by financials and consumer defensive stocks, while the S&P 500 dipped 0.28%. Risk-off sentiment was squarely aimed at AI hardware assets.
The market turbulence comes at a pivotal moment — right before Nvidia’s upcoming quarterly earnings report. Wall Street’s consensus forecast puts Nvidia’s revenue for the quarter at around $92 billion, with data center revenue expected to grow by more than 100% year over year. The fundamentals still point to explosive growth. In the first quarter of fiscal 2027, Nvidia posted revenue of $81.615 billion — up 85% year over year and 20% quarter over quarter, both record highs.
This round of Nvidia’s stock volatility is closely tied to rising U.S. Treasury yields, which are forcing a revaluation of growth assets. The 30-year Treasury yield has climbed above 5.3%, sitting at multi-year highs. As the risk-free rate moves up, it compresses the valuation multiples of growth stocks whose cash flows are weighted heavily toward the distant future. High-valuation assets are the first to feel selling pressure — and Nvidia is naturally ground zero.
Supply chain costs are also rattling investor sentiment. On August 24, reports emerged that some of Nvidia’s largest customers have been informed that servers powered by Nvidia’s AI chips will see price hikes exceeding 15%, driven by surging memory chip costs.
Sources familiar with the matter say the price increases apply to systems scheduled for delivery early next year, including those featuring the flagship Vera Rubin and Grace Blackwell chips. The exact magnitude of the increases will depend on which generation of Nvidia chips the systems use and their memory configurations.
It’s been reported that server assemblers contract-manufacturing for major data center operators like Microsoft, Google, and Oracle have recently notified customers of the price increases.
According to Morgan Stanley data, Nvidia’s next-generation flagship AI rack product, Vera Rubin, sells for approximately $7.8 million. The storage cost alone has skyrocketed from roughly $370,000 to $2 million — a 435% surge — and now accounts for 26% of the total system cost, up from less than 10% in the previous generation.
At the same time, the global compute supply landscape is shifting, with specialized inference chips rapidly coming to market. There’s growing concern that GPU dominance is gradually eroding — some inference workloads are being diverted to other architectures, and profit distribution across the supply chain is starting to shift toward memory, interconnect, and other segments. This is reshaping how the market views Nvidia’s growth ceiling.
Notably, Nvidia announced yesterday that its Groq 3 LPX rack has entered full mass production, marking the commercialization of technology acquired through the company’s largest-ever acquisition. The Groq 3 LPX rack is a core product of the Vera Rubin platform, engineered for ultra-low-latency AI inference.
Dion Harris, Nvidia’s senior director, said the Groq racks will be deployed alongside Vera central processors and Rubin GPUs on the platform of Nebius, a new cloud service provider, and are expected to go live later this year.
But the market is clearly more focused on the pace of commercialization and return on investment. Earlier, Nvidia teamed up with several top Wall Street institutions — including Blackstone, Goldman Sachs, and Apollo — to build a compute financing platform, aiming to mobilize over $500 billion in third-party capital to help downstream customers finance compute hardware purchases. The business concept is designed to expand customers’ purchasing power, but it has also sparked concerns about a “lending customers money to buy your own chips” circular financing model: if downstream AI businesses fail to generate returns as expected, debt risks could ricochet back to Nvidia.
Additionally, Nvidia’s equity investments in core customers like OpenAI and Anthropic have blurred the line between supplier and customer, prompting some institutions to scrutinize the potential risk points behind Nvidia’s revenue figures.
As for where the stock goes next, Goldman Sachs notes that for Nvidia to see a major post-earnings rally, simply beating expectations and raising guidance won’t cut it anymore — the company needs to deliver something big and new.
The Goldman Sachs team led by Schneider believes Nvidia’s current stock price trades at a significant discount to its assessed fair value, so there’s still room for upward revaluation — but only if three catalysts materialize: first, continued improvement in profitability metrics at hyperscale cloud providers to sustain capital expenditure growth; second, Nvidia maintaining prudent and controlled capital spending on its customer financing platform to ease concerns about circular supplier financing; and third, the company staying committed to aggressive share buybacks and dividend programs.
The team advises investors to watch five key pieces of information in Nvidia’s upcoming earnings: details on the customer financing platform and its impact on capital allocation; progress on Vera Rubin platform deployment in the second half of 2026; gross margin trends and upstream raw material costs; CPU demand driven by agentic AI; and shifts in the competitive landscape.