By NUPIAO News | Reporter: Song Jianan
Unitree Robotics, the humanoid robot leader that just landed on the STAR Market only a week ago, has put on a dramatic capital show in just a few trading days — a rapid correction from euphoric valuations back down to the reality of fundamentals.
When Unitree Robotics (688836.SH) opened for trading on August 19, its stock spiked to 1,100 yuan per share in the opening moments, pushing its total market value to 444.9 billion yuan. That set a new record for a registration-system IPO debut, with the highest profit per lot reaching nearly 475,000 yuan.
After several consecutive days of pullback, the stock was trading at 611.00 yuan by midday on August 26 — up 1.36% on the day, but with market value down to 247.1 billion yuan, a loss of nearly 200 billion in just one week. On August 25, the stock had dipped as low as 588 yuan intraday before closing at 602.8 yuan, with a total market value of 243.8 billion yuan — a maximum drawdown of 46% from its peak.
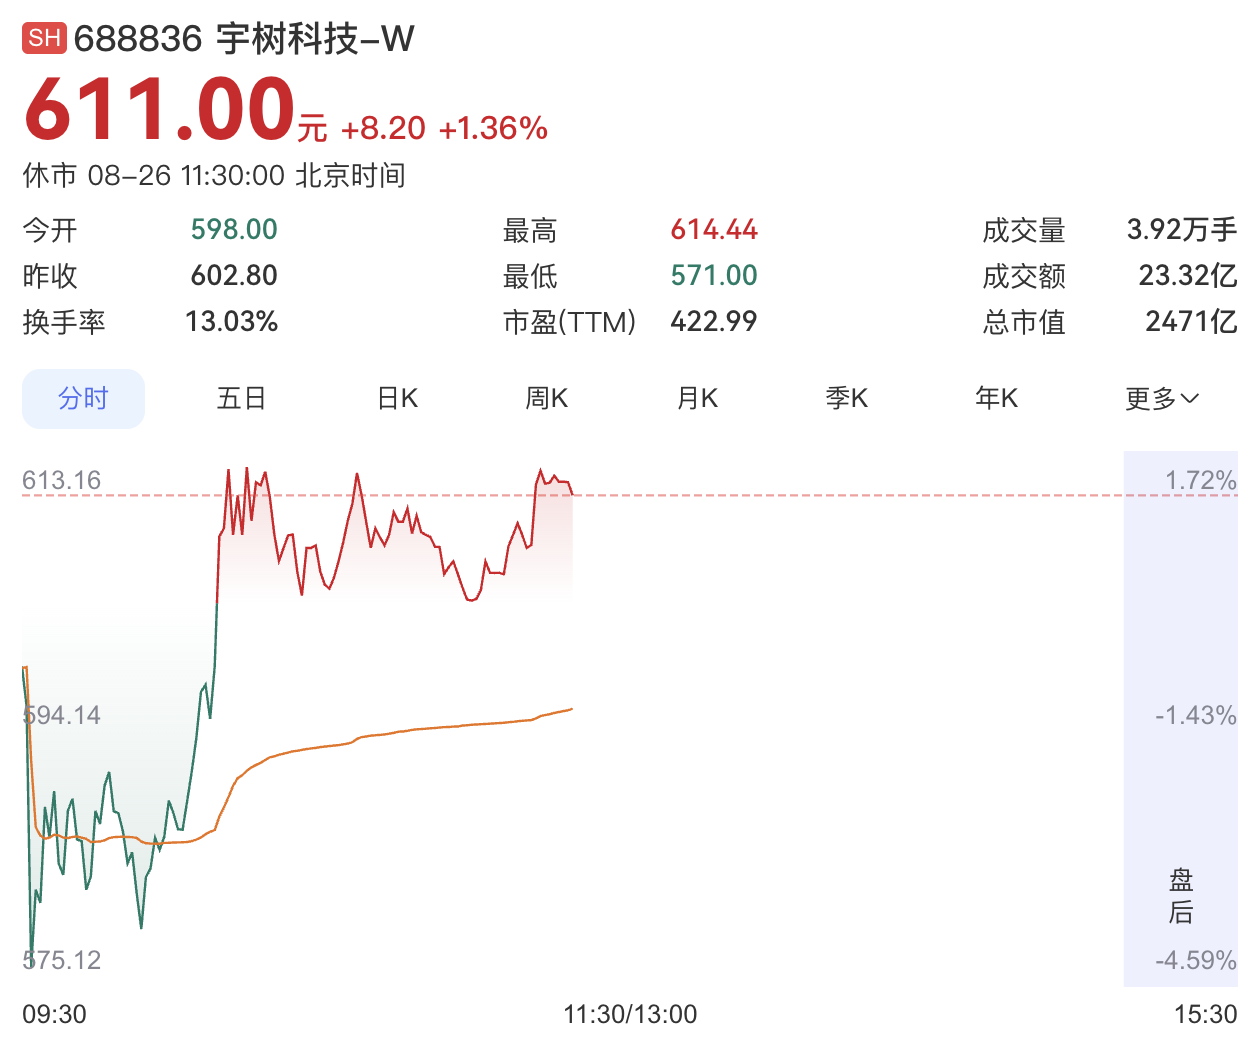
Still, the current share price remains significantly above the IPO price of 150.8 yuan. The static P/E ratio sits at 877 times, far exceeding the 38.56 times average for the general equipment manufacturing sector on A-shares.
Behind this violent price swing are multiple forces at play.
The float structure of new shares is the direct technical reason behind that crazy first-day spike. According to Unitree’s public offering documents, its freely tradable shares accounted for only 7.44% of total share capital in the early listing period. With such a limited supply of chips chasing the red-hot humanoid robot narrative, prices were bound to get bid up wildly. The 444.9 billion yuan peak was more of a liquidity-driven trading illusion than a consensus fair value.
Several international and local brokerages published research reports around the IPO, offering valuation estimates that stood in stark contrast to the frenzy in the secondary market.
On the first day of trading, Nomura initiated coverage with a “Buy” rating but set a target price of just 370 yuan — based on 25 times projected 2027 price-to-sales, implying a fair market value of around 150 billion yuan.
Nomura noted that Unitree designs and manufactures its own core components — motors, reducers, encoders, and driver boards — with outsourced parts accounting for only 10% to 20% of total costs. Gross margin expanded from 44% in 2022 to 60% in 2025. The bill of materials for humanoid robots has dropped below 100,000 yuan, and the R1 series is priced at just 29,900 yuan. The mature cash flow from its quadruped robots is funding R&D and market expansion for humanoids.
Moreover, within 26 months, Unitree iterated through four humanoid robot series — H1, G1, R1, and H2 — building a complete product matrix covering “mobility + manipulation + interaction.”
Nomura projects Unitree’s revenue for 2026-2028 at 2.687 billion, 5.396 billion, and 13.184 billion yuan, with year-over-year growth of 58%, 101%, and 144%, respectively.
But the firm also flagged three major risks. First, demand structure risk: in the first nine months of 2025, 73.6% of Unitree’s humanoid robot revenue still came from research institutions, with industrial or commercial applications at only about 5%. Second, FCC ban risk: on July 28, the U.S. Federal Communications Commission placed advanced robots manufactured by foreign entities on its “covered list.” Products that already received authorization can continue to be sold, but new models won’t be able to obtain FCC certification. U.S. market revenue share has already dropped from 18.39% in 2023 to 13.30% in 2025. Third, intensifying competition: in the first half of 2026, Unitree shipped roughly 5,900 units, but rival robotics company Agibot surpassed it with 8,400 units, knocking Unitree from the world’s No.1 to No.2. The average selling price for humanoid robots has also fallen from 593,000 yuan in 2023 to 166,000 yuan in 2025.
CITIC Securities, the lead underwriter for Unitree’s IPO, took a similarly grounded stance, pegging the target market value at 50.6-55.9 billion yuan. CCB International set a target price of 269 yuan, implying a market cap of around 109 billion yuan — just 24.5% of the opening-day peak. The consensus among institutions is that market trading prices have front-loaded years of industry growth expectations.
Slowing earnings growth is the underlying reason for widening investor disagreement. Unitree’s prospectus shows net profit attributable to parent of 278 million yuan in 2025 on revenue of 1.699 billion yuan, following years of explosive multi-fold growth. But in 2026, the growth curve shifted: first-half revenue came in at 1.152 billion yuan, up 48.54% year-over-year, while non-GAAP net profit fell 19.34% to 244 million yuan — a clear sign of rising revenue without rising profits.
Some analysts had already warned during the IPO phase that the 219 times issuance P/E ratio was premised on sustained ultra-high growth for years to come. If growth decelerates, the lofty valuation would be very hard for earnings to digest.
As for when embodied intelligence can truly hit its explosion point, Unitree founder Wang Xingxing said at the main forum of the 2026 World Robot Conference on August 20: “Embodied intelligent robots entering homes — in the best case, two to three years; in the worst case, five to ten years.” In his view, the core challenge for embodied AI to reach its “ChatGPT moment” lies in the alignment problem between AI model outputs and physical robots.
In his speech, he explained that language models are purely digital encoding, with almost no loss in input and output. But every time a physical robot executes a task, it introduces errors at the physical level, and the accumulation of those errors weakens the model’s generalization ability. That’s why robots still struggle with unfamiliar environments. Still, he believes the problem will be solved in the future.
There are also dissenting voices in the market. Some bullish investors argue that Unitree is one of the few profitable high-performance humanoid robot companies globally. In 2025, it shipped over 5,500 bipedal humanoid robots, and its hardware technology accumulation leads the industry. The traditional manufacturing valuation framework shouldn’t be applied to it, they say — hard-tech growth companies deserve higher forward premiums.
For Unitree Robotics, going public is just the starting line. The next question it must answer — the one the capital market cares about most — is whether it can turn the grand industry narrative into visible profits on the financial statements, step by step.