Staff Reporter |
Editor | Wen Shuqi
The aftershocks of the e-commerce tax policy are still rippling through the industry.
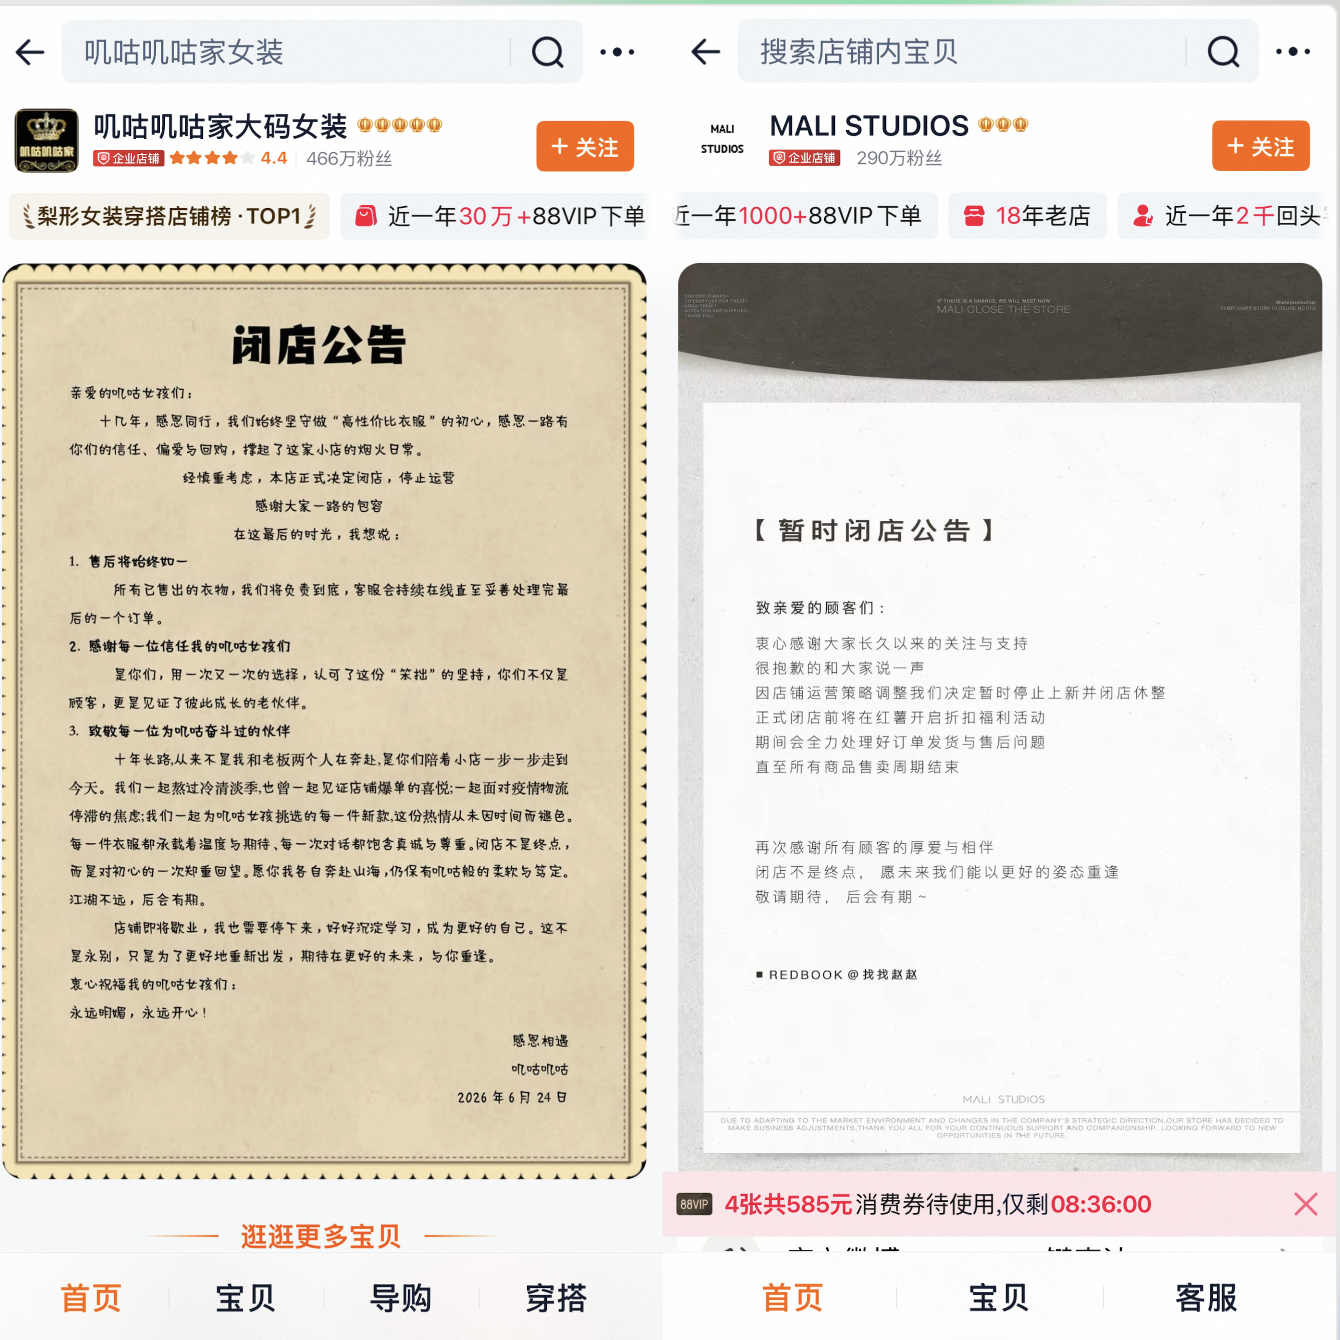
Late last June, “Jigujigu,” a top-tier Taobao store with 4.67 million followers and over 2 million annual orders, announced its closure. Before that, we already saw the women’s fashion shops of first-generation internet celebrities like Zhang Dayi and Zhou Yangqing, along with other once-popular stores like Shaonv Kaila, Liangliangjia Korean Chic Women’s Custom, Meiya 0413, and Luola Password—many boasting millions of followers and serious fan pull—all shutting down one after another.
A wave of internet-famous stores from a decade ago is now fading into silence. Their reasons for closing are strikingly similar: they rose on the back of channel-driven traffic in the early days, but today, squeezed by sky-high return rates in the women’s fashion sector and the added costs of e-commerce taxes, the math just doesn’t work anymore.
Gao Chuan, a veteran in Hangzhou’s apparel e-commerce scene, told us that starting with the tax enforcement, even more women’s fashion sellers will be thrust into a brutal elimination round this year.
The term “Tao Brand” is slowly becoming a relic of the last e-commerce era.
Around 2010, the first generation of “Tao Brands” burst onto the scene—Han Du Yi She, Inman, Three Squirrels, and others. Han Du Yi She even clinched the top spot in women’s fashion on Singles’ Day in 2013, enjoying a moment of unparalleled glory. But just two years later, Uniqlo snatched the crown. As international and traditional brands flooded into e-commerce and overtook them one by one, that first generation became “tears of an era.”
Recently, Yun Sheng, head of Taobao’s apparel merchant strategy, mentioned in an interview with us that the first-generation Tao Brands were limited by their mindset: “Merchants were just running a business,” churning out products that chased market trends—whatever was hot that year, they’d sell.
But the new generation of brands is different. Yun Sheng has observed that brands emerging on Taobao over the past couple of years “hit the ground running with a brand-first approach.” These merchants, often shortly after opening their stores, invest in brand advertising, prioritize getting customers to their shops via brand keywords, and meticulously craft everything from design to visual presentation to communicate a distinct aesthetic and brand identity.
In August this year, Taobao launched the “IFASHION Black Label,” handpicking an initial 17 original brands from among millions of merchants. The “Big Four” of Taobao women’s fashion—CHICJOC, KEIGAN, UNICA, and C’EST M—all made the cut, alongside Rongmei (the first Taobao fashion brand to go public), Meiyang MEIYANG, and edgier original labels like GFinnerthought, which Jackson Wang once promoted.
“There are plenty of brands on Taobao that aren’t yet household names, but their transaction volumes already surpass those of many listed companies. They’re the hidden giants of the industry, where brand recognition and sales figures just don’t line up,” Yun Sheng said. For these brands to keep growing—whether by expanding offline or venturing overseas—they need to break out of their niche and gain broader visibility.
These 17 brands sketch out the blueprint for the new-generation “Tao Brands” Taobao wants to cultivate, and they also reflect the platform’s current strategic bet.
Back in June 2025, the State Council released the “Regulations on the Reporting of Tax-Related Information by Internet Platform Enterprises,” mandating that platforms regularly report the identity and income details of businesses operating on them. By December, the State Taxation Administration disclosed that over 7,000 platform enterprises had already submitted such information, which in turn curbed practices like fake order brushing.
The cost of e-commerce taxes quickly began squeezing industrial-belt merchants.
Gao Chuan told us that many sellers used to source goods straight from wholesale markets, doing drop-shipping with just a five or ten yuan markup, relying on volume to turn a profit. But since wholesale goods rarely come with VAT invoices for deductions, their margins weren’t even enough to cover the taxes—so it’s only natural they’re being weeded out.
The traffic-dependent internet-famous stores mentioned earlier mostly fall into this category. They draw eyeballs through the owner’s fashion showcases, but their product lineup is typically sourced from industrial belts or wholesale markets, with little in the way of original design or factory backing.
“This year, a lot of Hangzhou apparel merchants are either pivoting to cross-border e-commerce or relocating their companies to Henan or Hebei,” Gao Chuan noted. The women’s fashion game is insanely competitive, and with Hangzhou’s high labor costs, there’s just not much room left for these types of sellers.
This aligns with what the platform is seeing. “Industrial-type merchants are really struggling to grow this year—tax compliance has brought on a prolonged period of pain that’s forcing them to transform. But original-design merchants on our platform are thriving, with overall growth hitting double digits,” Yun Sheng shared with us.
The apparel e-commerce market is massive and mature. According to estimates from the China National Textile and Apparel Council’s Circulation Branch, China’s apparel B2C online retail sales reached 2.38 trillion yuan in 2025, up 2.59% year-on-year, accounting for 14.9% of the nation’s 15.97 trillion yuan in total online retail. Chasing high growth on such a huge base is getting tougher by the day.
That’s why Taobao is putting such a strong emphasis on originality this year. Yun Sheng explained that looking at new merchant performance in Taobao apparel, two areas are showing clear momentum: one is original design—covering designers, stylized looks, and influencer-driven lines—and the other is large merchants with robust supply chains and operational muscle. “But in terms of growth potential, the original design track is clearly winning. It has a higher ceiling and moves faster.”
Apparel is also one of the most fiercely contested categories across e-commerce platforms, and each platform has settled into its own distinct groove.
Taobao leans toward a “shelf thinking” model—consumers come with intent, and brands sustain them through search, recommendations, storefronts, and membership programs. Xiaohongshu skews toward content, where brands spark interest through images, notes, lifestyle storytelling, and aesthetic narratives. Douyin tends to breed influencer-led fashion brands that scale quickly via key opinion leaders, but impulse buying also brings high return rates.
Gao Chuan has observed that “the ripple effects of the e-commerce tax are pushing quite a few merchants back to the shelf-based e-commerce of Tmall and Taobao—Douyin e-commerce has gotten tough too.” At the same time, Taobao is tightening its criteria for “original” certification. In the past, Taobao iFashion only required “original images”—owners were free to interpret styles as they pleased—but now, the products themselves must also be original designs.
The channel and traffic dividends that the previous generation of Tao Brands feasted on are long gone. Today’s brands first have to prove their taste and aesthetic, then leverage China’s manufacturing muscle for small-batch, fast-turnaround production to stand out from the crowd.
That said, these Black Label merchants have already outgrown Taobao alone. Most operate across Douyin and Xiaohongshu as well, extend their supply chains upstream, and push their channels offline . Take the Big Four of Taobao women’s fashion—they’ve built stable customer bases and solid cash flows, barely taken any outside investment, and achieved “hidden champion” status. The only thing missing is the buzz.
That’s precisely why Taobao wants to push these “Black Label” brands into the spotlight. When the new-generation Tao Brands grow their businesses big enough, the pie gets larger, transaction volumes climb naturally, and the platform can capture more revenue from brand-building efforts.
Still, breaking out of their niche isn’t a walk in the park for these new Tao Brands. Yun Sheng revealed that repeat purchase rates among Black Label brands’ loyal customers can hit as high as 80%. This highly sticky fan economy is their foundation, but it also locks them into a fixed demographic bubble.
This is especially true for brands built on influencers, where brand power is inherently tied to the founder’s personal IP—making the influencer themselves a wildcard. On top of that, breaking out means appealing to mainstream tastes. Is it better to chase broad traffic, or hold onto distinctiveness and brand tone?
Today, Taobao wants more people to see the value of these brands. As for when the new-generation “Tao Brands” that break out will truly go global, Yun Sheng’s answer is that it might take another “ten years.”