Staff Reporter |
Editor | Wen Shuqi
The buzz from WAIC 2026 hadn’t even faded when the robotics crowd gathered again in Beijing — this time, on an even bigger scale.
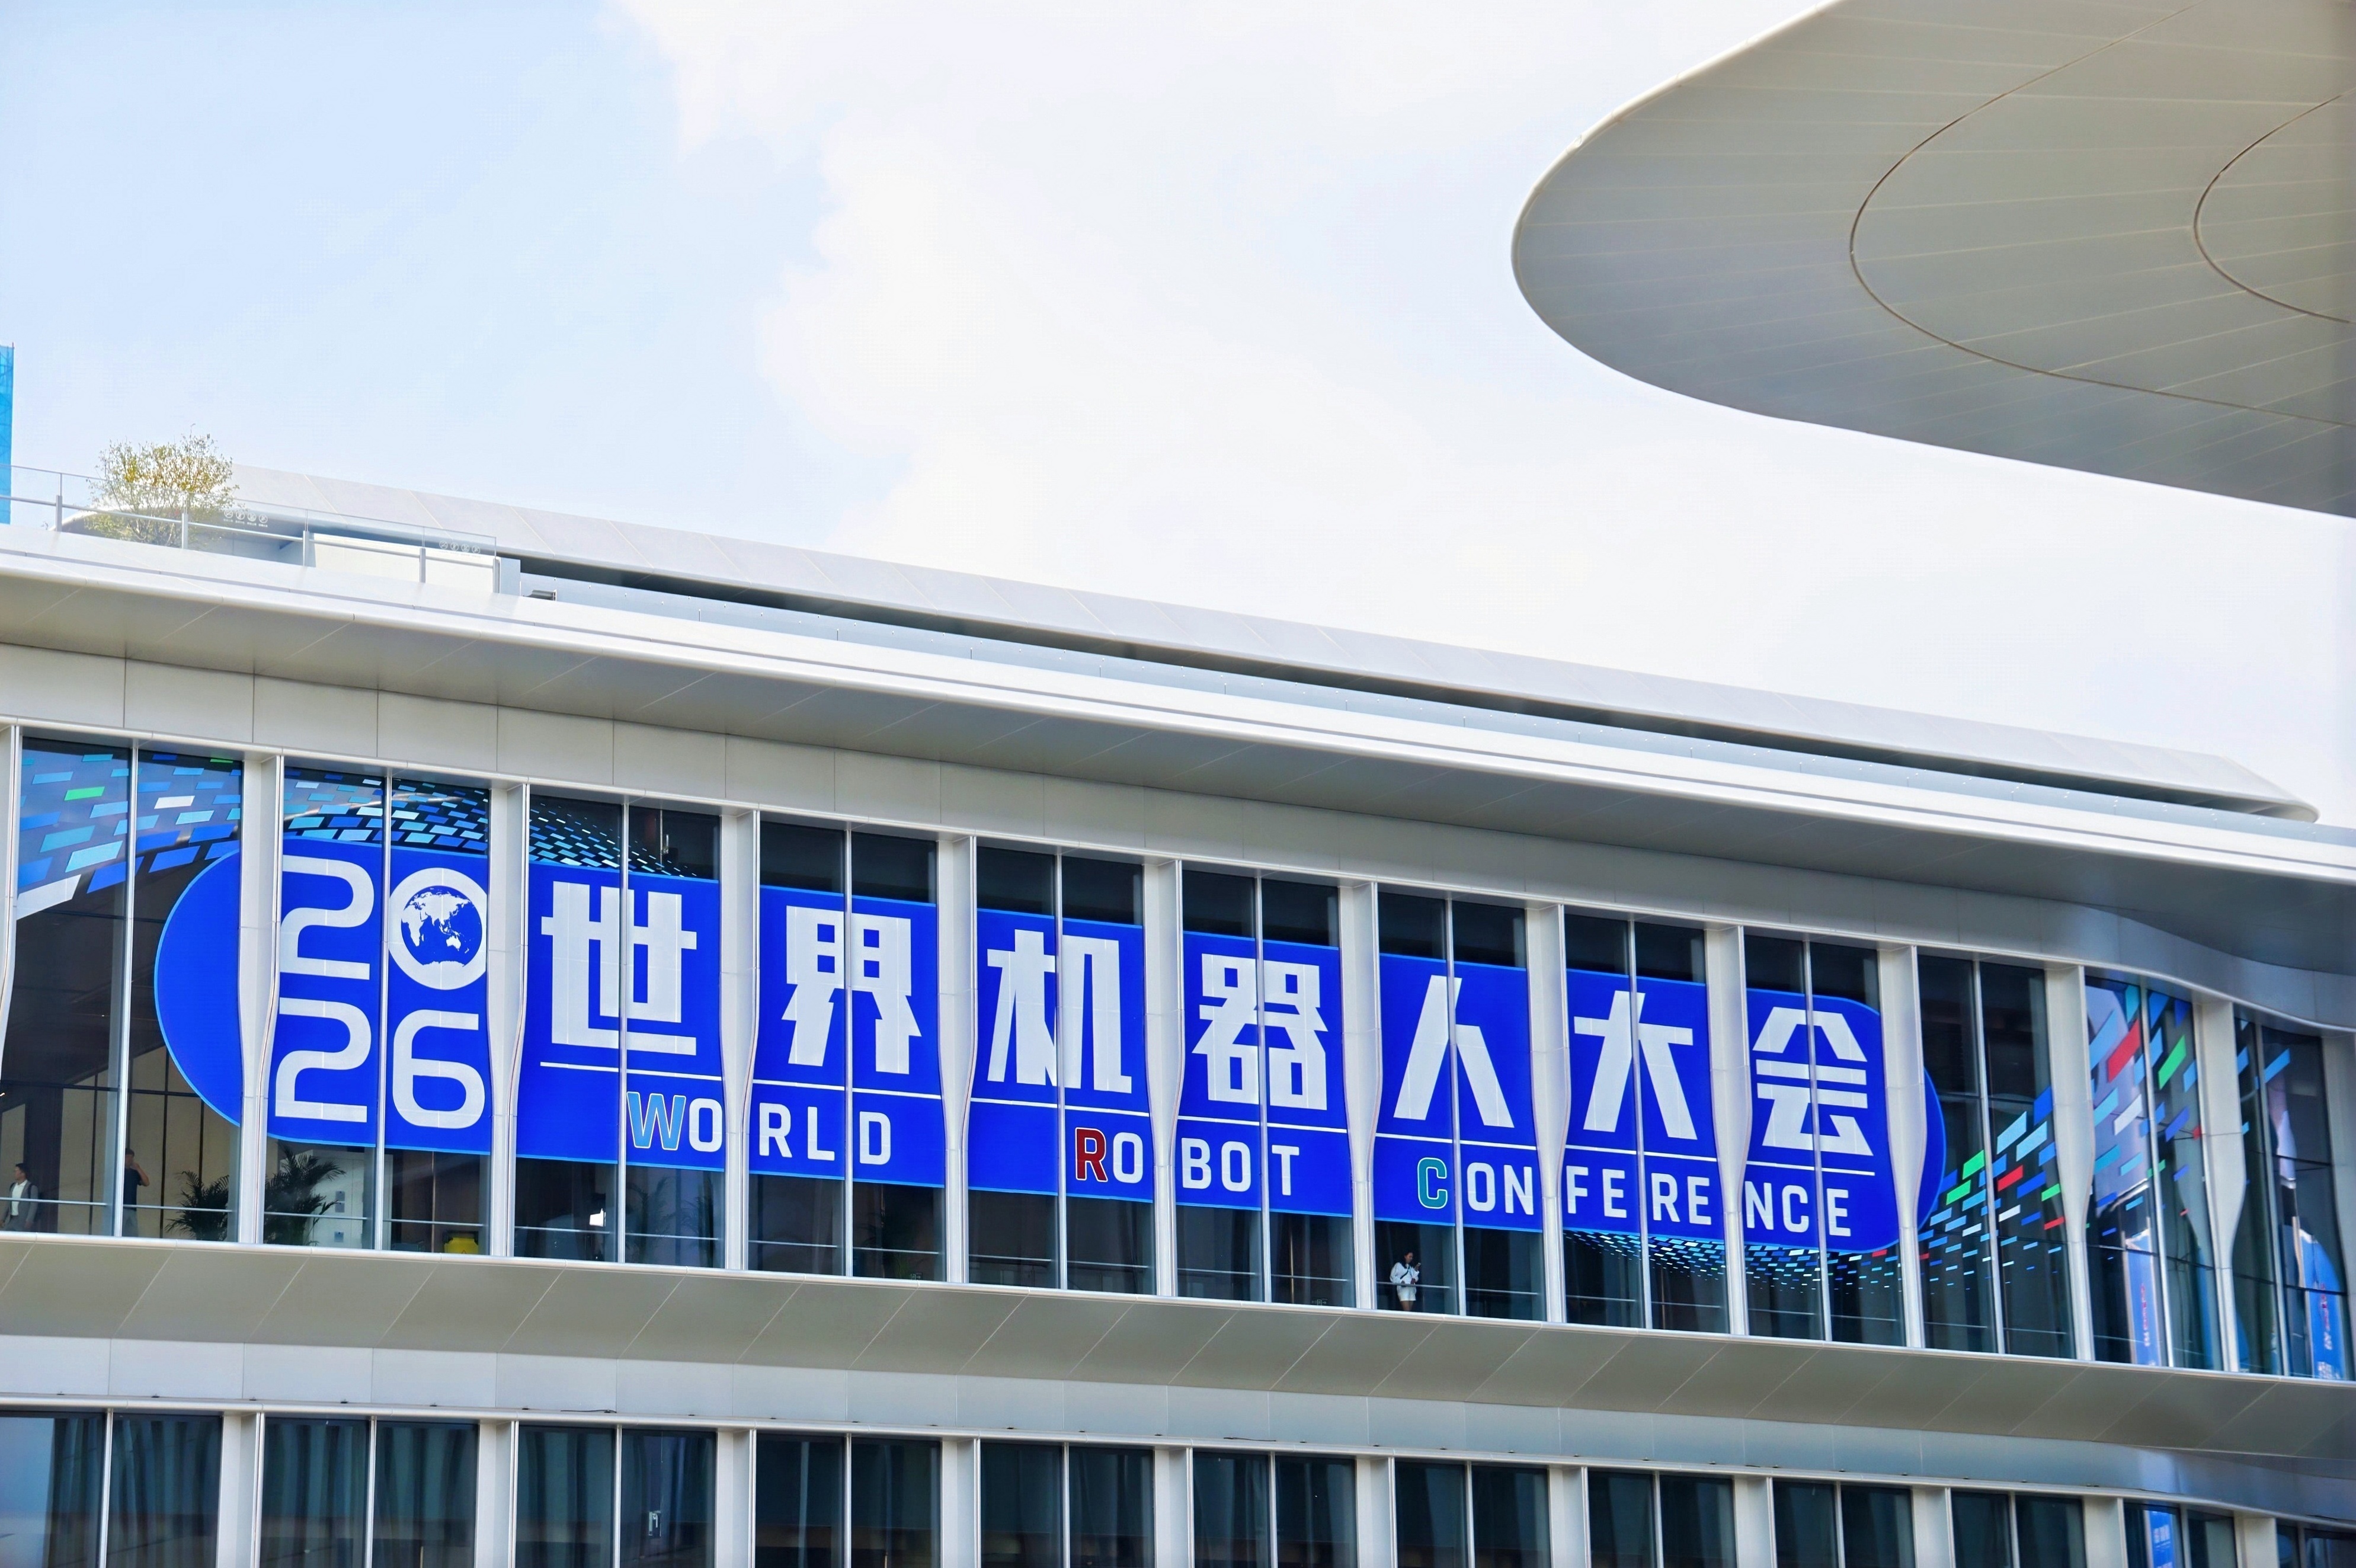
From August 19 to 23, the 2026 World Robot Conference (WRC) took over the capital, drawing over 300 domestic and international exhibitors and showcasing more than 3,000 products across four halls spanning nearly 50,000 square meters.
One shift we couldn’t help but notice this year: suppliers of reducers, motors, dexterous hands, and sensors are no longer content to hide in the corners of whole-machine exhibitors’ booths. They’re setting up their own standalone displays — and lots of them.
Behind these booths lies a supply chain that’s accelerating at full throttle. Numbers shared at the opening ceremony showed that in 2025, the robotics industry’s above-scale enterprises pulled in over 300 billion yuan in revenue, with an average annual growth rate topping 20% over the past five years. In the first half of this year alone, revenue hit 165.5 billion yuan, up 24.5% year-on-year.
Meanwhile, domestic embodied intelligence financing surged past 93.5 billion yuan in H1 — a fivefold jump from the same period last year.
The capital markets are also putting a heftier price tag on robots. On August 19 — the very day WRC kicked off — Unitree Robotics debuted on the STAR Market , briefly touching a market cap of 400 billion yuan. The next day, Unitree’s chairman, general manager, and CTO took the main forum stage. He didn’t talk stock prices. Instead, he zeroed in on just how far robots still are from true large-scale deployment.
Wang Xingxing pointed to generalization as the industry’s biggest bottleneck. In fixed scenarios, training can push success rates impressively high — but swap in a new object or environment, and performance nosedives. Unitree has had robots on automotive production lines since 2024, yet broad deployment remains elusive. The core issue is still efficiency and versatility that aren’t good enough.
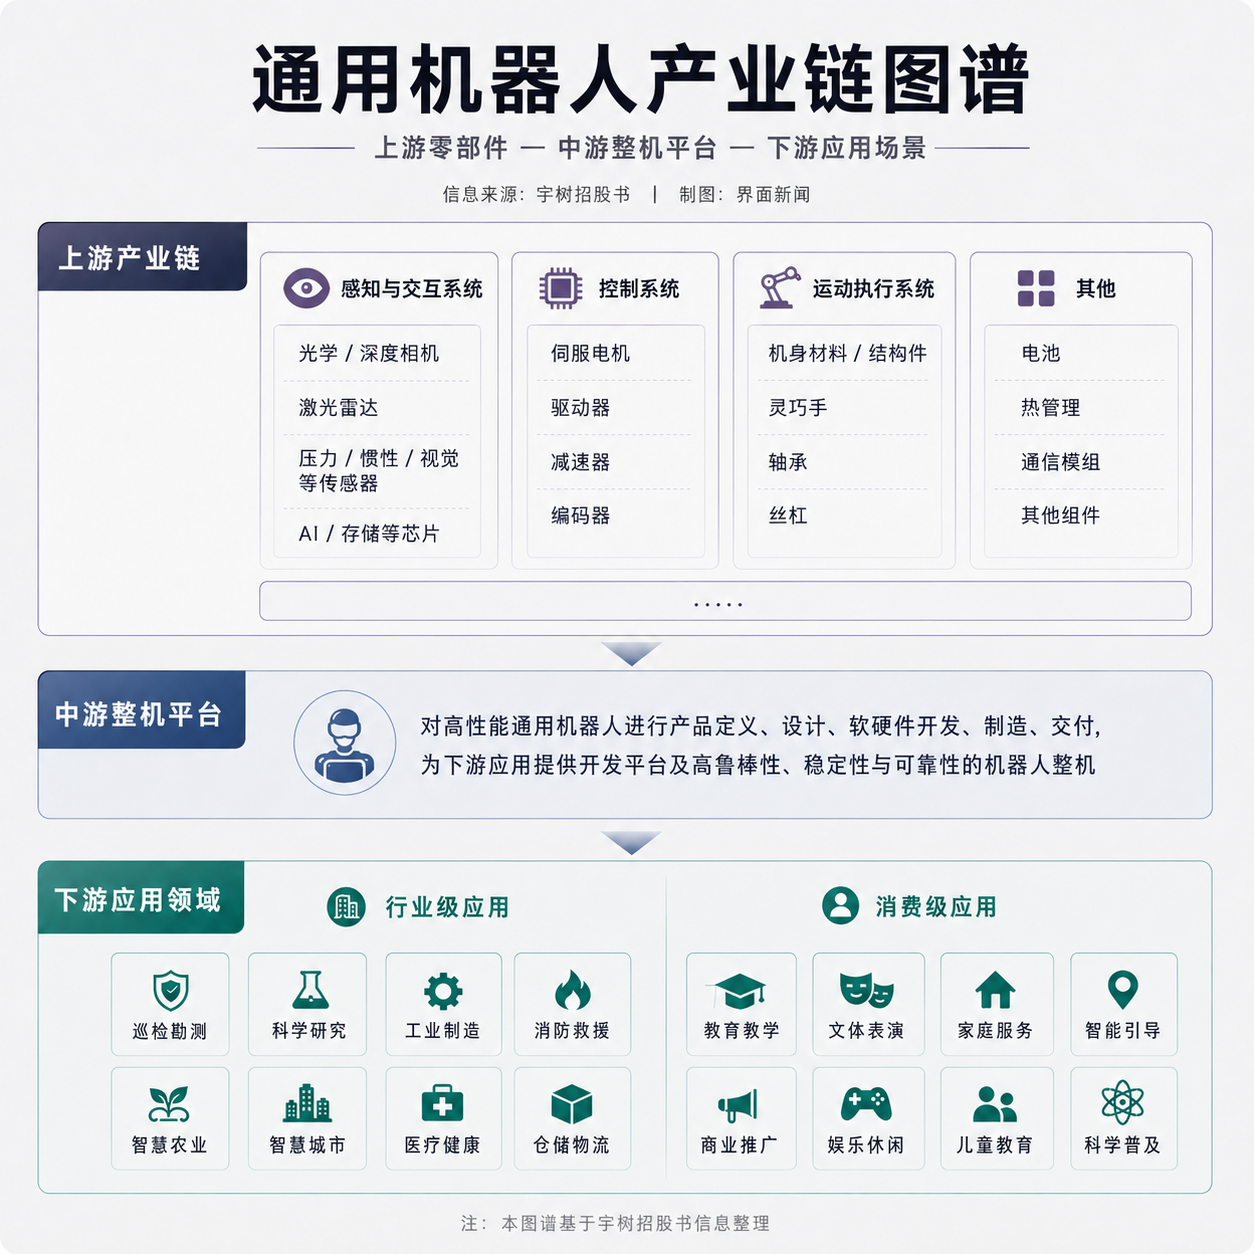
And tackling these problems is bigger than any single whole-machine maker going it alone. Whether robots can genuinely enter factories and daily life depends on reducers, motors, dexterous hands, sensors, and the deeper layers of data and simulation all maturing in sync.
The Hard Part Now: Consistency and Cost
A humanoid robot carries dozens of joints, each one a combination of reducers, motors, ball screws, and encoders, with dexterous hands and sensors at the ends. On stage, whole-machine makers compete over who can jump higher or run faster — but what actually makes that possible is what upstream suppliers can deliver.
On the reducer front, Wang Yunqi, assistant general manager at Fengli Intelligent, says the company started developing harmonic reducers a decade ago, benchmarking against top international players through both forward and reverse engineering. The industry’s best-in-class products boast a rated service life of 15,000 hours — and her team’s core specs are now getting very close. She adds, though, that the flexspline, one of the three critical harmonic components, still relies heavily on imported materials. Domestic substitutes are in active validation.
Still, technical routes haven’t converged the way many expected.
Her read: the mainstream consensus is taking shape — bipedal upper limbs use harmonic, lower limbs go planetary, quadrupeds run all-planetary, and wheeled platforms use harmonic in the waist and legs while upper limbs depend on actual working conditions. But the bigger wildcard is cost.
In plain terms, harmonic reducers were built for industrial automation where precision is king. But in many real-world humanoid applications, you don’t need that level of positioning accuracy — what you need is rigidity and a price that doesn’t make your CFO wince. That’s where planetary reducers step in as the more practical pick.
Zhang Yufeng, founder and CEO of Boundless Power, offers another angle. He points out that there’s still no industry-wide consensus on which joint modules the upper body should use. For big explosive movements like running, planetary is the crowd favorite — it’s cheaper and delivers serious burst power. But when it comes to fine manipulation, nobody touches planetary; its precision is an order of magnitude off from harmonic. He also floats a contrarian idea: if the AI model gets strong enough, it could actually lower the hardware bar, letting you swap harmonic for planetary without losing much.
Zhang runs the numbers. If the industry consensus of 20,000 humanoid robots last year holds, multiply that by a dozen or so joints per upper body, and the total market is still a fraction of the automotive industry. That means hardware refinement, cost reduction, and consistency will all be uphill battles.
He also cites a specific quality metric: Mean Time Between Failures (MTBF). Traditional industrial robots are expected to run 10,000+ hours. A two-finger gripper hitting industrial-grade millions of cycles over two to three years is no big deal. But dexterous hands? They can’t touch that. Nor can many other joints on the body.
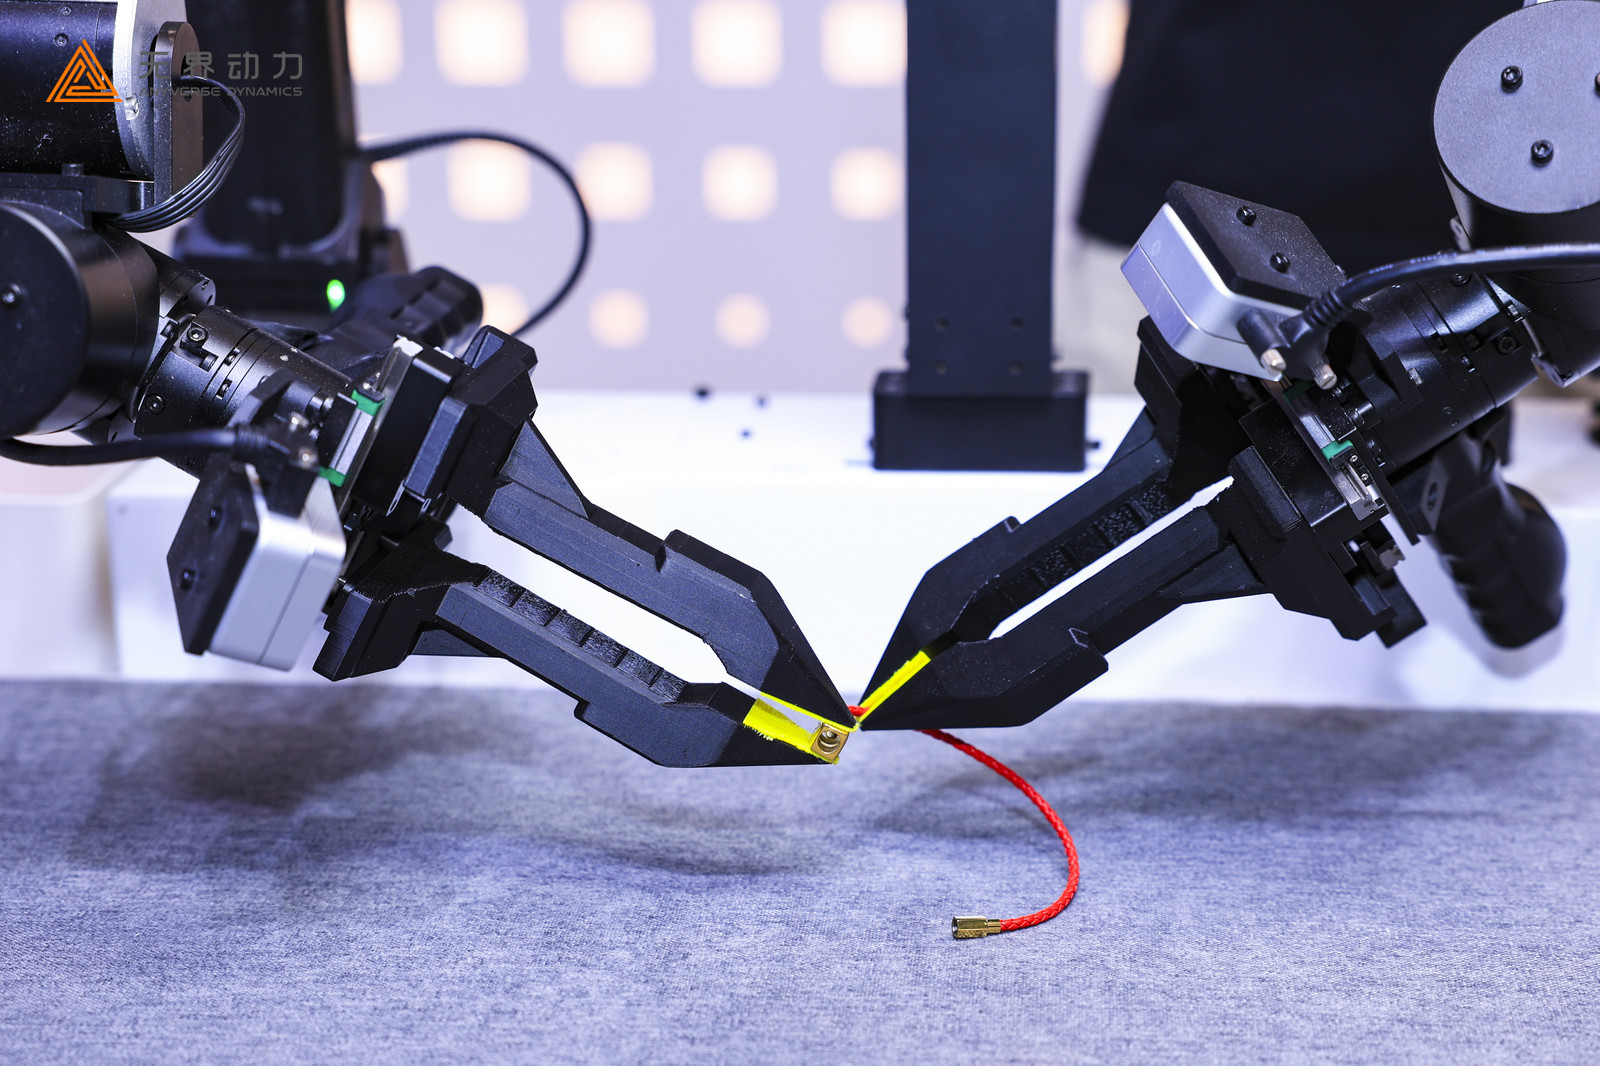
The same story plays out in motors. Xia Ji, technical director at Jindi Co., points out that frameless torque motors for large joints are mature both technically and cost-wise. The headache is the micro frameless motors for fingers and wrists. They’re tiny, but their internal structure is nothing like a toy motor. You’re packing a dozen-plus coil windings into a space the width of a pen, all done automatically by machines. After winding, you need rock-solid reliability with zero fluctuation in output torque — which demands brutal yield rates and process control.
Xia offers two metrics to judge quality. First: how densely copper wire fills the winding slots. The fuller the slot, the more torque you get from the same motor size with less heat. Second: if the motor gets stalled and keeps drawing current, its temperature should rise no more than 20 degrees Celsius within 30 seconds.
Achieving those numbers on a prototype is easy, he says. The hard part is hitting them on every single unit in mass production. The key lies in automated production lines — and there’s no off-the-shelf equipment for that. You have to co-develop with equipment makers, and that’s not a one- or two-year project.
Xia also warns against the cliff-edge demand curve: “This month 10,000 units, next month 100,000 — that’s practically a disaster for the entire supply chain.”
Dexterous hands face a different kind of split. Xu Jiansheng, marketing director at CAS Lingxi, says research customers care about stability, performance, and the development ecosystem, and they’re willing to pay a premium. Whole-machine makers, on the other hand, are brutally price-sensitive — the deciding factor for bulk orders is always unit cost. Right now, the sweet spot is products in the 10,000-yuan range with around six active degrees of freedom.
His take: scaling dexterous hands won’t just be about price. It’ll take better stability and longer service life, plus a clearly defined commercial use case that actually generates value.
A researcher at a dexterous hand startup told us that the three mainstream technical routes right now are linkage, direct drive, and tendon-driven. Direct drive is more common because control is relatively straightforward, but it runs hot — sustained reliable operation over long periods is the current hurdle.
On the chip front, things are stuck at an even earlier stage.
Huang Mei, VP at Embodied Intelligence, says global robot compute currently leans on general-purpose and automotive-grade chips as a stopgap, with overseas giants taking an early lead through their general-purpose ecosystems. She likens the difference to a general-purpose engine versus a nervous system. The former chases peak compute; the latter demands a closed loop of real-time perception, execution, and planning — with low power draw, low latency, and offline capability.
Huang notes that truly native embodied chips are still a blank slate. “But that’s also a golden opportunity for domestic players to break through.”
Beyond Hardware: The Invisible Gaps
You can quantify the gaps in upstream components with hard numbers, but some shortfalls are harder to spot with the naked eye.
During this year’s WRC, Lightwheel AI unveiled the first 100,000-hour-scale open-source multimodal human behavior dataset, EgoSuite-Open100K, along with the RoboFinals pilot base simulation evaluation infrastructure and the RoboStack real-world deployment and feedback platform. These three releases cover data, evaluation, and deployment feedback, respectively.
Yang Haibo, co-founder and president of Lightwheel AI, says they’re all pointing at the same thing: getting robots from the lab to the production line requires far more than most people realize.
The most visible gap is data. Yang’s take: large language models had decades of internet data to train on, autonomous driving had cars driving around the world, but embodied pretraining is nearly zero — because there’s no massive fleet of robots autonomously collecting data in the wild.
“This year, client demand is typically 100 to 1,000 times what it was last year. Last year it was hundreds to thousands of hours; this year it’s commonly hundreds of thousands to millions of hours,” Yang said in an interview. Once the volume scales up, the new headache is data inconsistency — different devices capture data in different formats with different annotations, making unified reuse nearly impossible. You need standards before you can turn data into a standardized product that flows at scale. Lightwheel AI also announced a “5-Year, 10-Billion-Hour Embodied Intelligence Data Co-Building Plan.”
Beyond standards, there’s an even more foundational gap: simulation.
Lightwheel AI is the only Chinese corporate member of the Newton Simulation Technical Committee, sitting alongside NVIDIA, Google DeepMind, Disney Research, and the Toyota Research Institute. Yang noted in media interviews that China remains relatively weak in simulation and heavily reliant on foreign tech — a dependency that’s both foundational and hidden, easy to miss.
Lightwheel AI’s fully self-developed simulation platform, SimFoundry, has already surpassed international leaders in point capabilities like cable solvers and soft-body solvers, according to Yang. The platform also supports domestic compute hardware.
From components to simulators, the gaps are scattered across every link in the chain. Xu Jiangmin, associate professor at Peking University’s Guanghua School of Management, says the robot supply chain is too deep and too finely segmented for vertical integration. Strategic collaboration is the way to go.
He flags two risks. First: don’t blindly expand capacity on the back of a single demand spike. The mainstream technical route hasn’t been settled, and an innovation at any one end could upend the entire chain. Second: you need to know which links absolutely require domestic substitution, and which ones can keep relying on foreign suppliers.
That kind of strategic collaboration already had concrete form at this year’s WRC. Fourier, for instance, showcased its “Embodied Home” full-stack embodied intelligence demo for home service scenarios — but it also brought its ecosystem partners — Qizhi Control, Yita Power, Yixing Lingguang, and Runke Energy — to exhibit together, embedding their sensors, joint modules, and data-collection headbands right inside Fourier’s own booth.
A Fourier representative said this exhibition model is about creating an entry point for external innovation into the robot industry ecosystem, letting scattered technologies accelerate validation around real products.
Beijing Humanoid Robotics, meanwhile, chose to lay its tech open for the industry. At WRC, it unveiled the unified embodied intelligence model Pelican-Unify, announced commercial availability for its embodied brain model Pelican-VL 2.0, debuted the lightweight Tiangong Omni (1.35m tall, 39kg), and opened up its underlying interfaces, motion control framework, and embodied manipulation capabilities.
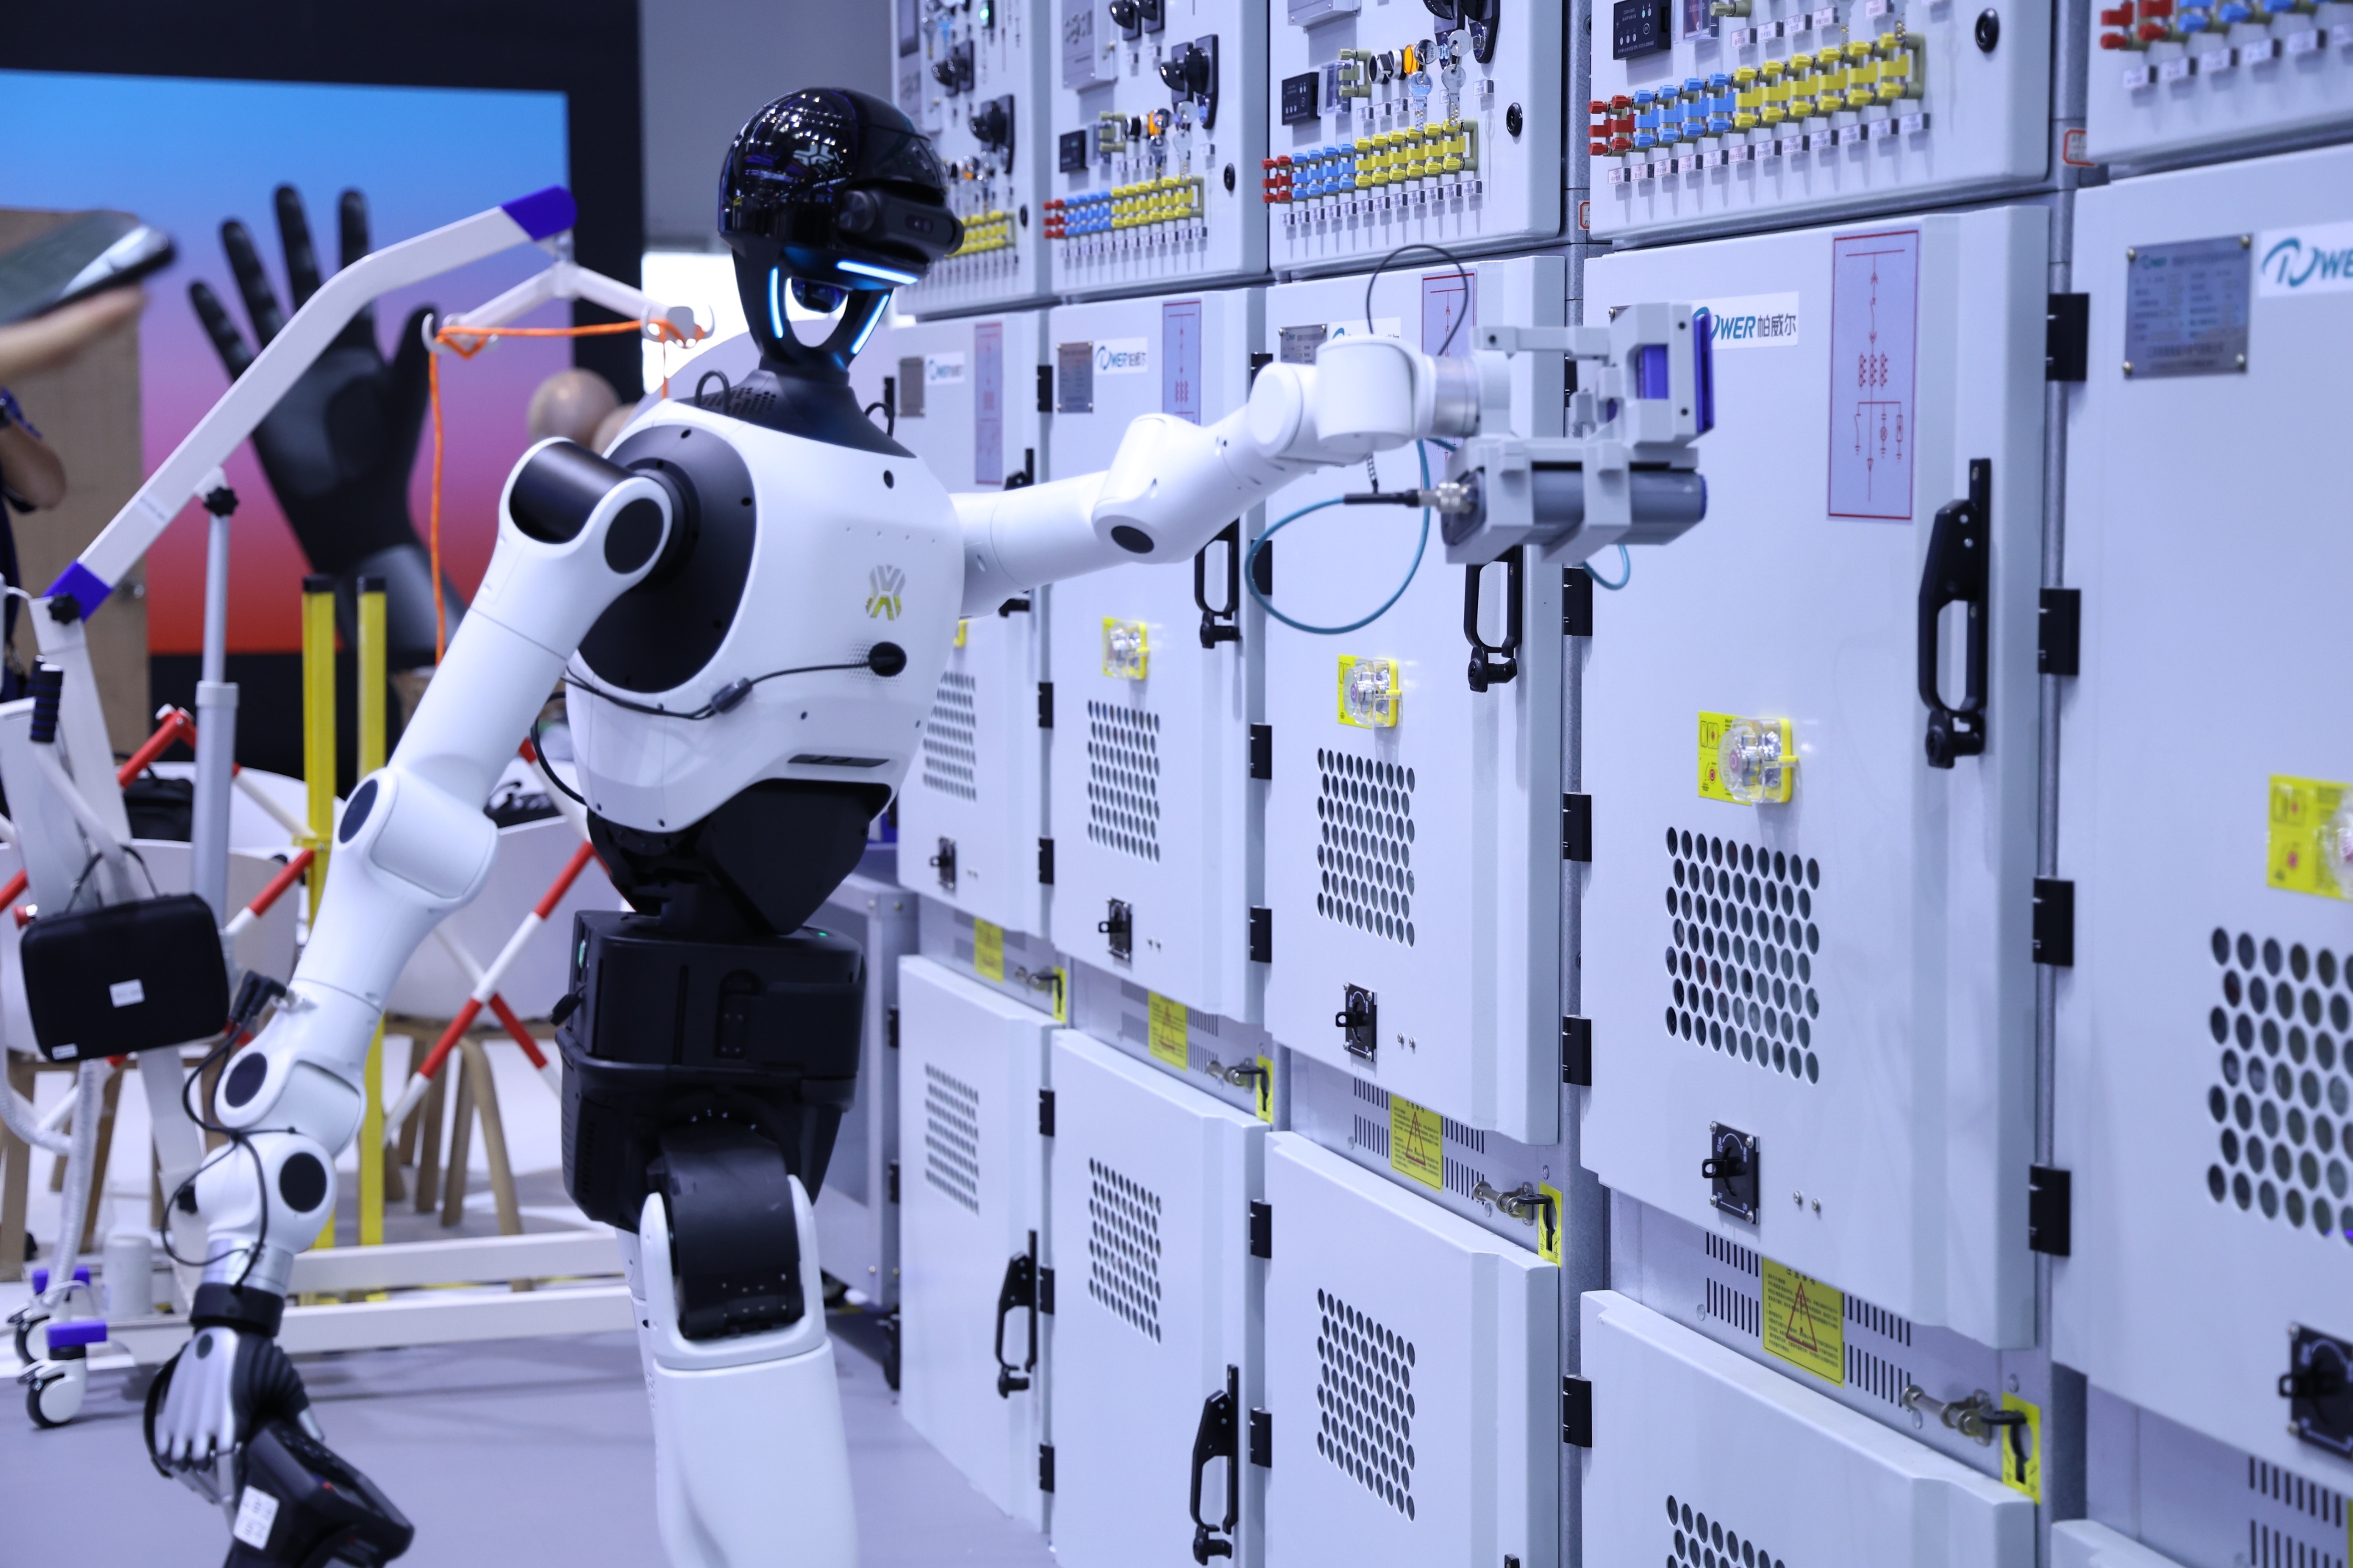
Xiong Youjun, CEO of the Beijing Humanoid Robotics Innovation Center, revealed in a media interview that the Huisi Kaiping platform’s open-source data downloads have surpassed 16 million, with more than a dozen open-source models and over 200 university partners doing secondary development.
Xiong notes that customers are now genuinely focused on ROI — a key sign the industry is maturing. The numbers for humanoid robots still don’t stack up as well as industrial robots, but the gap is closing fast.
From more component makers stepping into the spotlight to data, simulation, and open platforms becoming the main talking points, the industry’s focus is shifting from what a single machine can do to how mature the entire supply chain really is.