By NUPIAO News
Having a massive stash of tech reserves doesn’t automatically translate into Wall Street confidence. That’s the harsh reality for Alphabet, Google’s parent company, right now.
Since hitting its all-time high, Alphabet’s stock has been on a slippery slope, with its market value shrinking by a whopping $700 billion. Wall Street is starting to second-guess Google’s AI game plan.
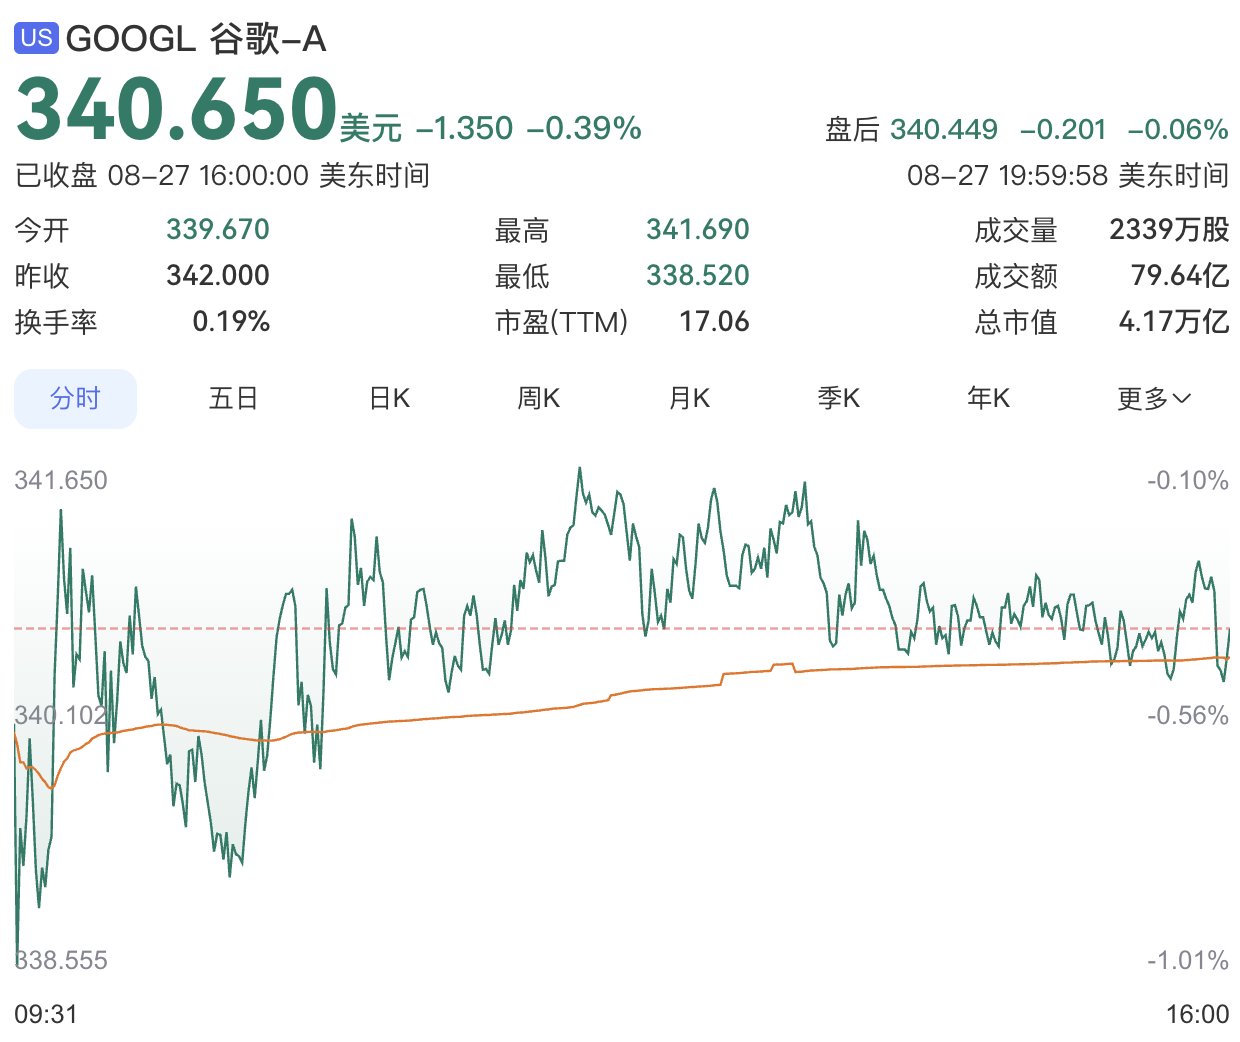
Back on May 17, Alphabet shares touched a 52-week high of $408.61, pushing the company’s total market value past the $4.8 trillion mark. At that point, everyone was betting on Google riding the Gemini wave to unlock fresh growth. But fast forward to the August 27 close, and the stock is sitting at $340.65, with market value hovering around $4.17 trillion. That’s a brutal 17% pullback from the peak — and in just over three months, a ton of paper wealth simply evaporated.
Here’s the kicker: Alphabet’s Q2 earnings were actually pretty solid. The company posted quarterly revenue of $119.8 billion, up 24% year-over-year. Google Cloud raked in $24.8 billion, a jaw-dropping 82% jump, and net income also saw a big boost — every single metric beat consensus estimates. But instead of rallying, the stock plunged 7.1% in a single day, erasing roughly $300 billion in market cap overnight.
So what’s spooking investors? It’s the financial strain from AI investments and a shifting competitive landscape. In Q2, Alphabet’s capital expenditures hit a staggering $44.92 billion. For the first time since going public, quarterly free cash flow turned negative — operating income just can’t keep up with the astronomical costs of building AI computing power. The company also raised its full-year capex guidance, with 2026 expectations bumped up to $195-$205 billion. And they’re planning to keep pouring money into data centers, TPU chips, and large model training. Translation: the cash-burning marathon is far from over.
To make matters worse, the competition is closing in from all sides. Microsoft has Azure cloud tightly bundled with OpenAI, and enterprise AI orders keep stacking up. NVIDIA is also expanding its enterprise AI ecosystem. Google might have the search traffic and mountains of user data, but its large model commercialization is moving slower than expected. Plus, there are persistent rumors that Gemini 3.5 Pro keeps hitting development delays.
And then in early August, Google CEO Sundar Pichai sent an email to the DeepMind team announcing a bunch of leadership changes. Specifically, DeepMind CEO Demis Hassabis is transitioning to become chairman of the division and Alphabet’s chief scientist. Meanwhile, Google’s chief AI architect, Koray Kavukcuoglu — who’s long been Hassabis’s right-hand man — is stepping up as senior vice president to take over most of Hassabis’s responsibilities.
On top of that, Jeff Dean, Google’s chief scientist who’s been shaping the company’s AI strategy for 27 years, is leaving. He’s teaming up with senior researcher Sanjay Ghemawat and others to launch an independent venture.
Investors are worried that this brain drain at the core AI team could slow down Google’s AI momentum. Alphabet’s response? They say the team is actively testing new model versions with partners and product iterations are still on track.
Given this tangled picture, Wall Street banks are clearly split. Goldman Sachs, in its latest report, highlighted that Google unveiled the Pixel 11 series, Pixel Watch 5, and its first Bluetooth tracker, the Pixel Tag, at the “Made by Google 2026” event, along with a showcase of next-gen Gemini Intelligence features. Even though hardware is a small slice of Google’s revenue pie, Goldman believes Google is embedding AI directly into devices through its custom chips and multimodal models, steadily gaining smartphone and wearable market share from a low base. The bank thinks expanding on-device AI features will boost Gemini’s utility and cement Google’s competitive edge in AI-era consumer internet. They’re keeping a “Buy” rating with a $435 price target.
Morgan Stanley’s team, led by Brian Nowak, also maintains an “Overweight” rating on Google with a reiterated $400 target. Their latest report notes that recent media coverage suggests Google has committed to supplying around 1 million TPUs for roughly $35 billion. “By our math, that’s about 1.3 gigawatts, which works out to approximately $270 billion per gigawatt based on our revised estimates. Previously, we assumed Google was selling racks and systems at about $200 billion per gigawatt in these first-party deals, with a 20% gross margin.”
Nowak’s team projects Google will sell 0.3 GW of TPU systems in the second half of 2026, ramping to 3.2 GW in 2027 and 4.2 GW in 2028. Based on these numbers, they estimate TPU-related Google Cloud revenue could hit $84 billion in 2027 and $108 billion in 2028.
But Barclays is singing a different tune. They’ve trimmed some of Google’s earnings assumptions and are cautioning investors about the runaway capex. The bank sharply raised its 2027 capex forecast for Google to $350 billion, and $500 billion for 2028 — both exceeding 100% of projected operating cash flow for those periods. That means Google will likely stay in negative free cash flow territory for the next two years.
With the stock under pressure, everyone’s watching Google’s next moves closely. On the product front, the market is waiting for Gemini 3.5 Pro to actually ship, and checking whether the new multimodal model Gemini Omni can deliver commercially and close the experience gap with rivals. On the enterprise side, Google Cloud needs to keep proving that high AI cloud growth can offset the hefty compute costs and gradually lift overall margins.
The rollout of the next-gen self-developed TPU is also on everyone’s radar — if TPUs can meaningfully replace purchased GPUs, that would ease the capex burden significantly. Beyond that, the mass adoption of AI-powered search and the developer ecosystem growth for the Antigravity AI agent platform are key variables that will determine whether Google’s AI story continues or falls flat.