By NUPIAO Staff
Enflame Technology, one of the “Big Four Domestic GPU Startups,” is set to begin its STAR Market subscription process this week.
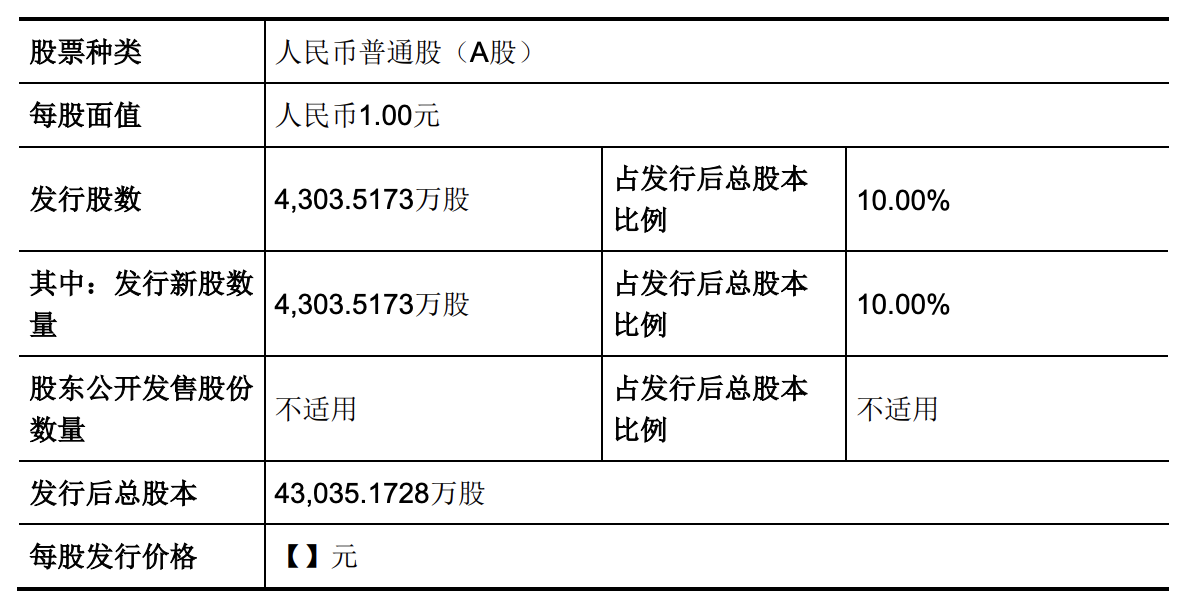
According to the issuance schedule, Enflame kicks off its IPO subscription this week, having conducted preliminary price inquiries on August 28. An online roadshow is slated for August 31 to finalize the offering price, with formal online and offline subscription opening on September 2. The company plans to publicly issue 43.0352 million new shares, representing 10% of the total post-issuance share capital, which will expand to 430 million shares. The total funds to be raised are estimated at 6 billion yuan.
According to Enflame’s prospectus, all proceeds will be channeled into chip R&D and supply chain development. This includes three major projects: R&D and industrialization of the fifth-generation AI chip series, R&D and industrialization of the sixth-generation AI chip series, and an advanced AI software-hardware collaborative innovation initiative. The funds are primarily earmarked for next-gen chip iteration and the enhancement of the TopsRider software stack, aiming to match the performance of top-tier international AI chips and fill the gap in domestic computing power.
CITIC Securities serves as the sponsor for this issuance, with Guotai Haitong Securities and GF Securities acting as joint lead underwriters. If the company remains unprofitable at the time of listing, its shares will be directly placed into the STAR Market’s growth tier upon debut.
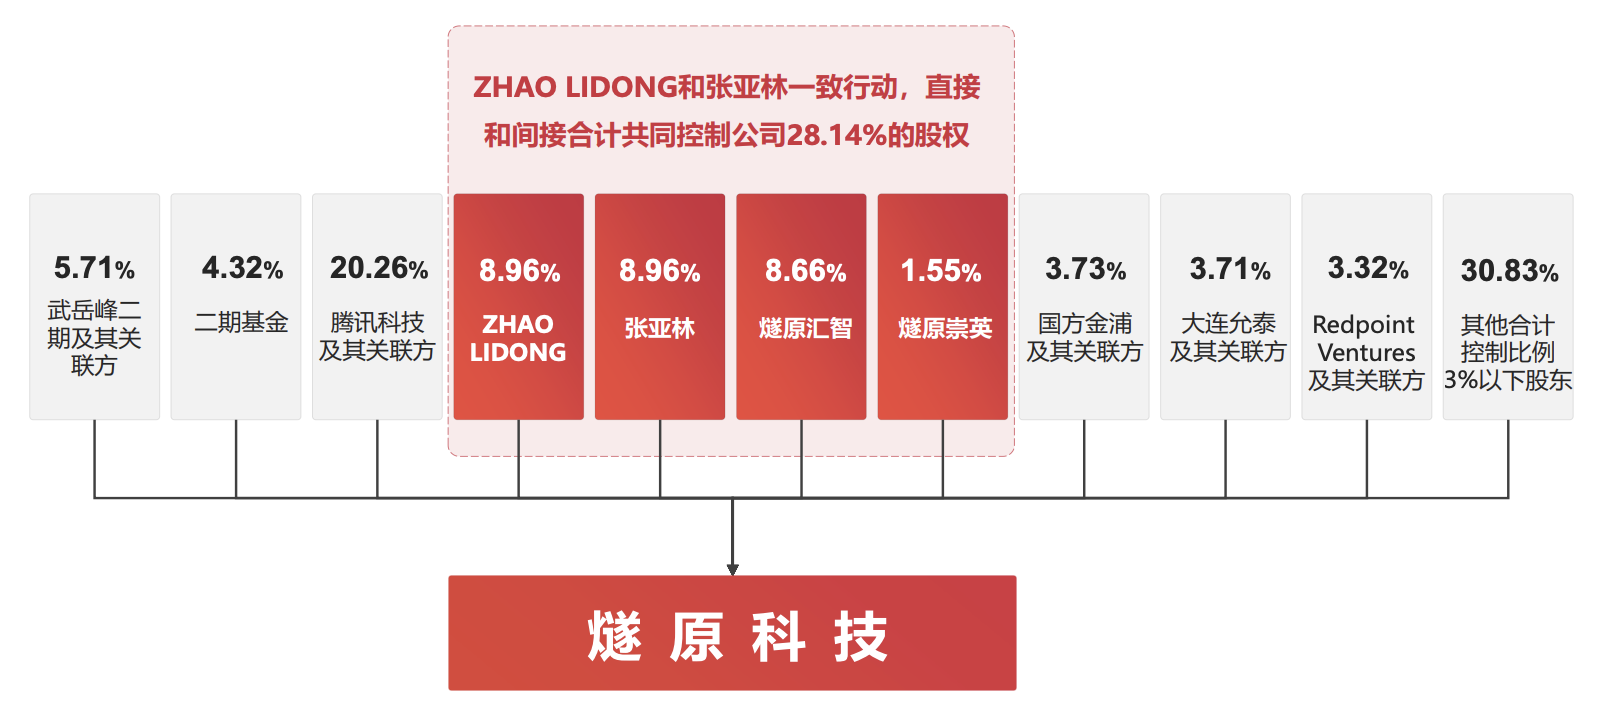
Public records show that Enflame Technology was founded in Shanghai Lingang in March 2018 by Zhao Lidong and Zhang Yalin. Both founders boast years of core R&D and management experience at AMD—Zhao has over three decades in the chip industry, while Zhang previously led the R&D and mass production of Microsoft’s Xbox One main chip. The two serve as co-actual controllers, jointly holding 28.14% of the company’s equity directly and indirectly, with no single controlling shareholder.
Notably, Tencent Technology is not only the company’s largest external shareholder—holding a combined 20.26% stake along with its concert parties—but also Enflame’s single biggest customer.
Over its eight-year history, Enflame has completed the self-developed iteration of five cloud AI chips across four generations, establishing a comprehensive product ecosystem encompassing AI chips, AI accelerator cards and modules, intelligent computing clusters, and a full-stack programming software platform. The company has chosen the DSA (Domain-Specific Architecture) route, developing its proprietary TopsRider software stack that operates independently of the CUDA ecosystem. Its products primarily target AI inference scenarios, while the company is also pushing forward the commercialization of its training-inference integrated offerings.
As of the end of 2025, the company employed 838 people, with 643 in R&D—accounting for 76.73% of the workforce. It has accumulated 313 domestic invention patents, positioning it as a representative player in China’s cloud AI chip sector.
Financial data reveals the industry-wide trait of high growth coupled with persistent losses. From 2023 to 2025, the company’s revenue stood at 301 million yuan, 722 million yuan, and 990 million yuan respectively, reflecting a compound annual growth rate of 81.32%. However, net profits excluding non-recurring items were -1.567 billion yuan, -1.503 billion yuan, and -1.197 billion yuan over the same period, meaning the company has yet to turn profitable and carries a substantial cumulative deficit.
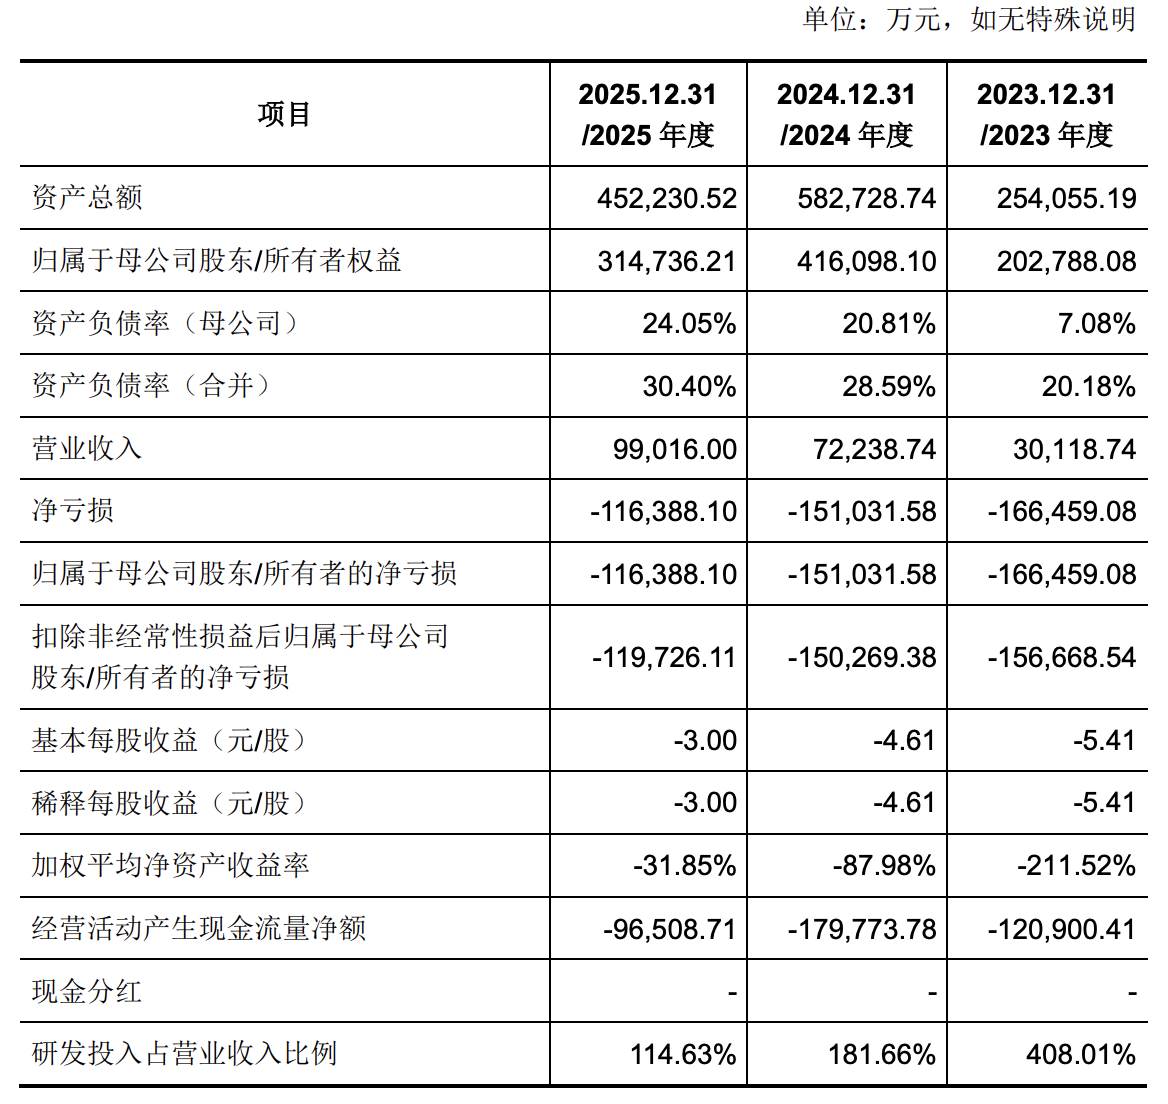
In its prospectus, Enflame attributes the losses to the enormous R&D investment required for cloud AI chips—both hardware and software stacks demand sustained heavy spending—while customer validation and adaptation cycles are lengthy, preventing revenue from covering fixed R&D costs.
The company projects its revenue for the first three quarters of this year to land between 2.3 billion and 3 billion yuan, a staggering year-on-year surge of 325.78% to 455.36% compared to 540 million yuan in the same period of 2025. On the profit side, the company remains in the red, with expected net losses and attributable net losses ranging from -860 million to -700 million yuan—a narrower deficit than last year, with loss reduction ranging from 3.13% to 21.15%.
Enflame emphasizes that, assuming revenue meets expectations and gross margins hold at moderate levels, it could essentially achieve consolidated break-even in 2026, though profitability might also be deferred to 2027.
The prospectus further reveals that, during the reporting period, direct sales to Tencent Technology plus related-party sales under the AVAP model (Approved Vendor Approved Price) accounted for 33.34%, 37.77%, and 83.79% of revenue in 2023, 2024, and 2025 respectively—meaning over 80% of 2025 revenue came from this single related customer. The partnership dates back to 2019, and after years of collaborative software-hardware refinement, Enflame’s products have been deployed extensively across Tencent’s various AI operations.
Enflame states that its current customer strategy is “single-point breakthrough first, then expanding from point to line,” concentrating limited resources on top-tier internet clients. However, it also flags the risk outright: any major shift in Tencent’s procurement strategy, or slower-than-expected expansion of new customers, would directly impact the company’s business performance.
Beyond customer concentration risk, the prospectus lists several other real-world challenges. Most of the company’s products are currently used in inference scenarios; its fourth-generation training-inference integrated product, the L600, has completed tape-out but has yet to achieve mass production and delivery, leaving uncertainty around the pace of adoption in large-scale model training scenarios. Additionally, operating under a Fabless model, the company relies on external suppliers for wafer fabrication, memory, and certain EDA tools, meaning shifts in the international trade environment could trigger supply chain disruptions.
At the industry level, NVIDIA commands nearly 60% of China’s AI accelerator market. Meanwhile, multiple domestic peers are competing fiercely, and tech giants like ByteDance and Alibaba are also developing their own AI chips, intensifying competitive pressure.
Furthermore, the company’s operating cash flow remained negative throughout the reporting period, and its prepayment amounts are relatively high, posing additional challenges to working capital management.
With Enflame’s subscription now underway, all of the “Big Four Domestic GPU Startups” have made their way to the capital markets. Moore Threads and MetaX have already listed on the STAR Market, while Biren Technology opted for a Hong Kong listing. Domestic AI computing startups are experiencing a concentrated window of capitalization. That said, the four companies are at different stages of development—some have already achieved partial profitability, while others remain in heavy investment phases. Their technical approaches also diverge into two main camps: GPGPU-based general-purpose GPUs and DSA-based specialized AI chips.
The AI computing market holds vast potential. According to CIC Consulting forecasts, the global AI accelerator chip market will surpass $500 billion by 2028, with China’s domestic market expected to exceed one trillion yuan. But domestic chip makers face a formidable road ahead: they must close the gap with overseas giants in both hardware and software ecosystems, while also ramping up commercial deployment and achieving self-sustaining profitability.